Features

Patrick Strake Franklin Street multifamily Texas quote

Major multifamily markets in Texas, beleaguered by an onslaught of supply as developers chased new renters moving to the state during the COVID pandemic, are beginning to see signs of recovery. But it’s one that looks dramatically different not only between cities, but also from one submarket to the next. Rents are roughly flat in Dallas and remain below year-ago levels in Austin, Houston and San Antonio after two to three years of decline, says Patrick Strake, managing director with Franklin Street. And depending on the submarket, apartment renters are jockeying for, and receiving, significant concession packages relative to the rest of the United States, he adds. According to the Federal Reserve Bank of Dallas, those include six to eight weeks of free rent (and as much as 10 to 12 weeks in some submarkets). “Texas is still going to be a great spot for capital for years to come, given its job growth and business-friendly nature,” adds Strake, who is based in Austin and leads Team Texas, the firm’s statewide multifamily investment sales platform. “But right now, equity is being highly selective, because the four big metros are coming out of a supply wave on four different timelines.” Hardest …
FacebookTwitterLinkedinEmail

The editors of REBusinessOnline.com are conducting a brief online survey to gauge market conditions in 2027, and we welcome your participation. The survey should only take a few minutes to complete. Questions range from property sectors that you are most bullish on heading into 2027 to trends in deal volume to your outlook for interest rates. The results of our 16th annual survey will be compiled and published in the January issues of our regional magazines. Conducting these surveys is part of our mission at France Media to provide readers with indispensable information, and we couldn’t do it without your help. Note: Please remember to click on “done” to properly submit the survey.)

FacebookTwitterLinkedinEmail
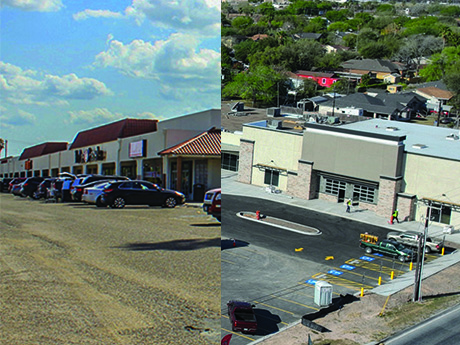
Palm-Plaza-Weslaco-Texas-Before-After

By Kirk Cypel, chief development officer, CBG Real Estate Americans are still spending, but the headline numbers tell only part of the story. Federal economic data shows that the economy grew at a 3.4 percent annualized rate in the third quarter; September retail sales rose 6.3 percent from a year earlier, and the unemployment rate was at 4.2 percent. Yet inflation-adjusted disposable income fell 0.3 percent in September, the savings rate slipped to 3.8 percent and real spending was essentially flat. Consumers are spending more dollars without necessarily getting more stuff. Higher-income households account for a disproportionate share of discretionary purchases, while middle- and lower-income consumers increasingly focus on necessities, convenience and value. Even in the same trade area, some retailers thrive while others struggle. As such, the logical conclusion is that owning a shopping center is less about filling boxes than assembling a tenant mix that meets consumer needs and encourages shoppers to return. Traditionally, three retail categories drive shopping centers: general merchandise, grocery and restaurants. Other services may fill space, but most are destinations for a specific errand or appointment, with less spillover for neighboring stores. A good tenant mix needs both dependable occupants and businesses that help …

FacebookTwitterLinkedinEmail
Justin Wheeler Berkadia quote

Berkadia recently partnered with the Chen Institute for Global Real Estate Finance at NYU Stern School of Business for the third annual Multifamily Investment Case Competition, held October 15–16. The competition brought together graduate student teams from leading business schools across the country to explore how technology can enhance investment returns in the multifamily sector. Participants were challenged to develop strategies at the intersection of apartment operations, technology and innovation financing — areas that do not often converge in traditional business school curricula. “Berkadia was honored to partner with NYU Stern for the third year in a row, highlighting our commitment to supporting young professionals and future leaders in real estate,” said Justin Wheeler, Berkadia’s CEO. “Engaging with eager, thoughtful participants and judges with deep expertise in the multifamily industry was both exciting and inspiring. This event was made possible by the dedication of university teams, fellow judges and NYU’s sustained support.” This year’s competition included teams from NYU Stern, Columbia Business School, UCLA Anderson, the University of Wisconsin–Madison’s School of Business, the University of Florida Warrington College of Business and the University of Texas at Austin McCombs School of Business. An accomplished group of industry leaders served as judges, …

FacebookTwitterLinkedinEmail
Gill-Pull-Quote

By Justin Gill, president, Allied Elevator The roof consultant recommends replacement. The mechanical contractor proposes a plant upgrade. The facilities team wants funding for an aging elevator, while the leasing team has already committed the next available budget to tenant improvements. Each request may be reasonable. The owner still needs a defensible answer to a harder question: which expenditure belongs in this year’s capital allocation plan, and what happens to the others? A useful answer starts with the consequence of deferral, not the persuasiveness of the latest proposal. Building systems compete for capital, but their proposals rarely arrive with the same evidence, assumptions or definition of urgency. Owners and asset managers need a common decision-making process without pretending that a roof, a cooling plant and an elevator fail in the same way. Remove Immediate Obligations Some findings require action before an ordinary budget ranking can be constructive. For example, a documented unsafe condition, an enforceable code requirement or a condition that prevents lawful operation needs immediate evaluation by the appropriate professionals. It should not be scored as merely another discretionary improvement and deferred because a different project has a more attractive financial profile. The owner should distinguish those obligations from …

FacebookTwitterLinkedinEmail
Reid-Pull-Quote

By Robert Reid, principal, Corporeal Visions Inc. Every multi-unit retail and restaurant operator knows the math on a late opening. Rent starts on the commencement date whether the doors are open or not. Staff have been hired and trained against a date that is now moving. Marketing has been spent. Equipment is sitting in a warehouse accruing storage fees. A four-week slip on a single restaurant can easily cost tens of thousands of dollars in carried rent, payroll and lost sales, and for a team opening several units a year, those slips compound. What separates the teams that open on time from the teams that don’t is rarely the quality of the finishes or the size of the budget. It is whether the general contractor (GC) was made to own a handful of coordination points that fall between the cracks of a typical bid. Facility and construction managers who put these items on the table before the contract is signed, and hold the GC to them through turnover, tend to open when they said they would. Demand A Written Lndlord-To-Tenant Handoff Most late openings trace back to the first week, not the last. A tenant build-out starts on the assumption …

FacebookTwitterLinkedinEmail

By Justin Elder, President, Elder-Jones, Inc., and President, Retail Contractors Association Whether a retailer is opening a new location, refreshing an operating store, converting an acquired property or rolling out a new prototype, construction comes with variables. Permits move at different speeds. Existing conditions do not always match record drawings. Electrical gear, HVAC equipment, storefront systems and owner-furnished fixtures may carry long lead times. Late design or merchandising changes can ripple through procurement, sequencing and store-opening plans. Those conditions may be unavoidable. Cost and schedule surprises often are not. The difference is disciplined preconstruction, clear decision rights, reliable project controls and a contractor who understands that the job site is also a retail environment. During a roundtable discussion at a recent RCA Annual Conference, experienced retail contractors shared lessons from decades of work. Their central message was straightforward: strong relationships matter, but the best partnerships turn trust into a repeatable operating process. Start with a technically complete preconstruction process The most effective time to solve a construction problem is before crews mobilize. Retailers should bring the contractor into the process early enough to test the drawings against field conditions, procurement realities, operating requirements and the proposed schedule. For remodels and …

FacebookTwitterLinkedinEmail

By Matt Willson, Holland Construction Services The pipeline of heavy industrial construction in the United States has never been larger or more demanding. Driven by a wave of reshoring, domestic manufacturing investment and landmark federal legislation, companies like Samsung, TSMC, Hyundai, Panasonic and Ford are committing tens of billions of dollars to new production facilities across the country.  Samsung alone is investing $17 billion in semiconductor fabs in Taylor, Texas. TSMC has committed more than $65 billion to three fabrication plants in Arizona. Ford and SK On are building a $5.8 billion electric vehicle (EV) battery campus in Kentucky.  The scale is extraordinary. And it is exposing a hard truth about conventional construction: The traditional field-built model cannot keep pace. The labor math doesn’t work The construction industry entered 2025 needing 439,000 additional workers just to meet existing demand. This number rose to approximately 500,000 by 2026, according to workforce data tracked by the Associated Builders and Contractors. The shortage is structural, not cyclical. Roughly 41 percent of today’s construction workforce is projected to retire by 2031, and 92 percent of contractors already report difficulty filling open positions. Forty-five percent have experienced project delays in the past year attributable directly …

FacebookTwitterLinkedinEmail

A lack of quality inventory is one of the prominent factors shaping the retail investment sales landscape. Simply put, there is more capital seeking retail opportunities than there are assets available for purchase, says Michael Marks, executive director of retail capital markets with Cushman & Wakefield in Chicago. Strong leasing activity and rising rents are bolstering investor confidence in the retail market, he adds. Amid historically low vacancy, U.S. retail asking rents grew 2.2 percent year-over-year to $25.65 per square foot triple net, according to Cushman & Wakefield’s second-quarter report. Structural supply constraints continue to support sustained rent growth, as the development pipeline represents less than 0.3 percent of existing inventory.  Retail investors are firmly in acquisition mode, according to JLL’s second-quarter U.S. report. In the first half of the year, retail investment sales volume reached $33 billion, up 14 percent year-over-year and the strongest first half since 2022.  Evan Lyons, executive vice president with West Bloomfield, Michigan-based Encore Real Estate Investment Services, poses the question — where does the next wave of inventory for transactions come from?  “Some will come naturally through ownership transitions, partnership changes, fund lifecycles and other reasons investors need to sell,” predicts Lyons.  “Debt maturities …

FacebookTwitterLinkedinEmail
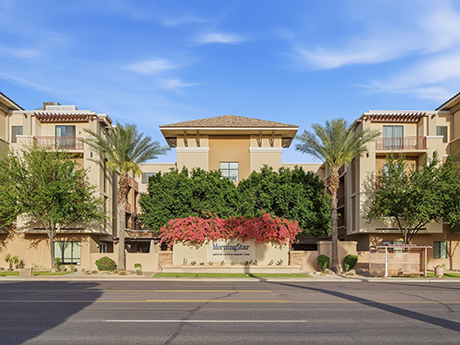
MorningStar-Arcadia_Phoenix

By Beth Mattson-Teig Healthcare REITs are well-capitalized, and they’re putting that significant financial muscle to work with big moves to expand their seniors housing portfolios.  As the world’s largest healthcare REIT with a market capitalization of nearly $170 billion, Welltower Inc. (NYSE: WELL) continues to dominate the investment market. Year-to-date through mid-August, Toledo, Ohio-based Welltower had a staggering $15.5 billion in new investments that it had closed or under contract, and another $6 billion in deals in the pipeline.  A major focus for the REIT has been expanding its Seniors Housing Operating Portfolio (SHOP) platform. SHOP allows REITs to share in the operational upside of properties compared to the fixed rents with traditional triple-net lease structures (see sidebar). Across the industry, there is no shortage of mega-deals. American Healthcare REIT Inc. (NYSE: AHR), based in Irvine, California, recently announced plans to acquire eight seniors housing properties managed by Kensington Senior Living for $873 million.  Earlier this year, Chicago-based Ventas Inc. (NYSE: VTR) announced a $540 million deal to acquire a majority stake in an 11-community luxury senior living platform owned by the Wolff Co. It’s no secret that REITs have been active buyers for the past several years. “This external …

FacebookTwitterLinkedinEmail
Newer Posts