Market Reports

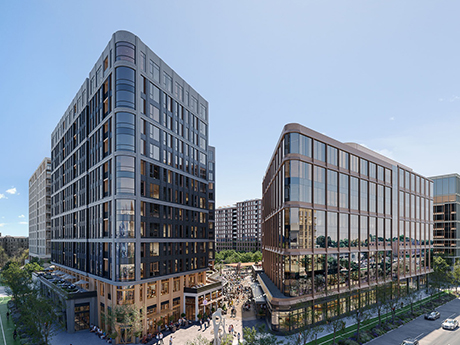
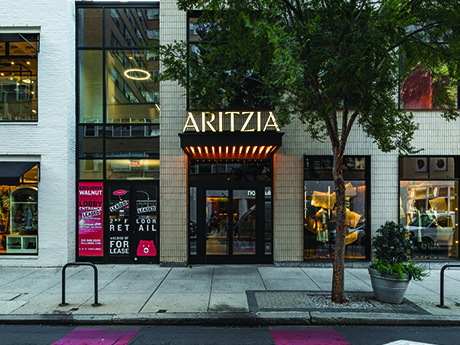
Aritzia-Rittenhouse-Square-Philadelphia

By Taylor Williams “People are still spending money.” That’s what Nick Skeparnias, principal at Agora Commercial Realty Partners, a full-service advisory and development firm, identifies as the single-biggest point of optimism about the state of the greater Philadelphia retail market. According to data from the U.S. Commerce Department, U.S. retail sales totaled roughly $774 billion in August, a 1.2 percent increase over the previous month. The Wall Street Journal also reports that spending in discretionary categories of retail, namely electronics and appliances, rose by 1.6 percent in August versus July. And according to both The Journal and Breitbart, the actual volume of retail sales in August exceeded economists’ expectations by anywhere from 40 to 70 basis points. Within Skeparnias’ simple, five-word declarative statement, there’s no question that “still” is the operative term. “Retail is only as good as the money that people have to spend on it,” he elaborates. “So when you consider the biggest concerns for this asset class, there’s nothing specific to retail itself, but issues that are more global. There’s always going to be something at the retail level; first it was e-commerce, then COVID-19. Now we have AI [artificial intelligence], and if that starts taking people’s …
FacebookTwitterLinkedinEmail

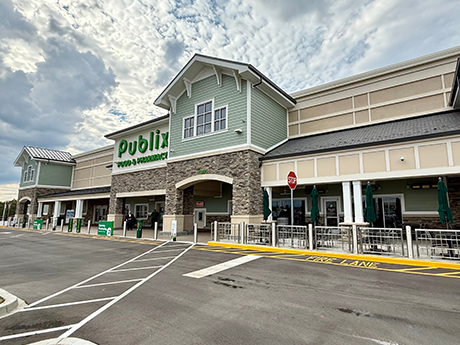
Retail investment gained meaningful momentum during the first half of 2026, reflecting growing confidence in market fundamentals and long-term consumer demand. While the national vacancy rate sits at 6 percent, Louisville’s current vacancy rate for retail is at 3.9 percent, according to the “Q2 2026 Cushman & Wakefield National Retail Report.” The Louisville market continues to demonstrate many of the characteristics that retail investors value: established trade areas, strong grocery-anchored corridors, limited new construction and a growing number of national retailers making long-term commitments to the market.  Retail real estate remains particularly strong in the eastern and northeastern portions of Louisville, with grocery-anchored space continuing to perform well. Cushman & Wakefield research also points to continued investment and new development taking shape across the market.  Louisville has seen roughly $165 million in shopping center transactions close over a recent 12-month stretch, driven heavily by private capital and 1031 exchange buyers. The properties that consistently attract attention are those with strong visibility, established traffic patterns, durable tenancy and demographics that support long-term consumer spending. Publix reshapes map Perhaps the clearest example of where Louisville retail is heading is Publix. From an investment perspective, we believe the significance of Publix goes well …

FacebookTwitterLinkedinEmail

By Teresa Borgen, Newmark From record-high leasing rates to historically low office sales volume, the Minneapolis-St. Paul market continues to present a complex and evolving landscape. Still recovering from lasting effects of COVID-19 and civil unrest during 2020, some submarkets are thriving, while others continue their gradual recovery. Here’s a synopsis of what’s happening in the market.   The haves and have-nots While the Minneapolis central business district (CBD) has been among the slowest downtown office markets in the U.S. to recover since the pandemic turmoil of 2020, recent activity suggests the submarket is showing signs of revival. Several high-profile relocations among national law firms underscore the trend, with firms such as Husch Blackwell, Cozen O’Connor, Faegre Drinker, Saul Ewing and Robins Kaplan making long-term commitments, some even growing their footprint.  The Minneapolis CBD has also attracted several recent relocations from the suburbs, with tenants like HNTB, Yardstik and Pepper Foster Consulting moving for enhanced accessibility to public transit and easier opportunities for growth. Given the migration to suburban office markets between 2020 and 2022, these moves and expansions are encouraging signs for the Minneapolis CBD, as well as other downtown markets in the U.S. While these developments are certainly …

FacebookTwitterLinkedinEmail
InterFace-Austin-Multifamily-Investment-Sales-Panel

By Taylor Williams AUSTIN, TEXAS — For more than a decade coming out of the Great Financial Crisis, the Austin growth story sold itself to the multifamily investment community, and at the height of the market, faith in that narrative alone might have been enough to sway an investment committee to tour, underwrite, offer and close. The past several years have seen a major departure from that modus operandi, as Austin has perhaps borne an outsized share of pain and erosion of fundamentals amid the larger U.S. apartment boom. Back are the days of basis resets, granular scrutinization of line items, skepticism of below-market exit cap rates and highly bifurcated submarket performances. It’s an inverted version of the multifamily utopia that prevailed throughout the state capital in times of historically low interest rates, and to confidently buy in Austin today requires conviction that the current state of affairs is only temporary. Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe. So spoke a handful of multifamily investment sales professionals at the annual InterFace Austin Multifamily conference, which took place …

FacebookTwitterLinkedinEmail

The Louisville MSA remains a leading logistics and manufacturing hub in the Midwest and Southeast. While growth continues, the market is transitioning from the rapid expansion and speculative development that followed the pandemic toward a more measured and sustainable pace. Louisville’s appeal begins with its strategic location. UPS Worldport, direct access to Interstates 64, 65 and 71, and a deep regional labor pool reinforce the market’s attractiveness to occupiers serving both national and regional supply chains. Manufacturers, automotive suppliers, e-commerce companies and third-party logistics providers increasingly view Louisville as a cost-effective alternative to larger and more expensive distribution markets. Like many industrial markets across the country, Louisville is currently absorbing a significant amount of new inventory delivered throughout 2025 and the first half of 2026. As a result, vacancy has risen to approximately 5.6 percent, up from the low- to mid-3 percent range that characterized the market for several years following the pandemic.  Even so, leasing activity remains healthy, particularly among users seeking modern Class A facilities with higher clear heights, trailer storage capacity and convenient access to major transportation corridors. One of the most notable trends in 2026 has been the slowdown in speculative construction starts. This is a …

FacebookTwitterLinkedinEmail

— By Adam Riddle of MMG Real Estate Advisors — After a difficult stretch, Denver’s rental market is showing signs of relief. Absorption picked up sharply in the second quarter, with renters absorbing more new apartments than developers delivered. This is the first time that’s happened on a trailing 12-month basis since late 2021. It’s a meaningful shift after two years defined by heavy construction and soft pricing. The supply wave that pressured the market is receding. New deliveries are down nearly 40 percent from a year ago, and the number of units still under construction has shrunk to less than 4 percent of existing inventory, well below the 2023 high of around 11 percent. A handful of submarkets, particularly Englewood/Littleton, still carry a sizable pipeline worth watching, but for most of the metro, the worst of the construction overhang appears to be behind it. Rent trends have been the last piece to catch up. Average effective rents are still down from a year ago, a lingering effect of the concessions landlords leaned on to fill units during the delivery wave. Thankfully, the quarterly trend has turned positive for two straight quarters now. Occupancy is climbing too, albeit gradually. Taken …

FacebookTwitterLinkedinEmail

For industrial developers and owners, Kansas City is an easy sales pitch right now.  “Two years ago, we had to scrounge around [for capital partners] trying to get phone calls returned. Now, they’re calling us saying they’re ready to see what we’ve got,” said Nick Cook, a development manager with Panattoni Development Co. “You’re always trying to sell a story to these folks. And Kansas City is a pretty easy one to sell right now. When it comes to speculative development, we’re feeling bullish.”  Cook’s remarks came during the developers, owners and investors panel at the InterFace Kansas City Industrial conference, which took place Tuesday, Aug. 18 at the Intercontinental Kansas City at the Plaza. Robert Ciston, a senior principal with BRR Architecture, moderated the discussion.  Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe. Fellow panelist Grant Harrison, executive vice president of development with VanTrust Real Estate, also expressed a bullish mindset on Kansas City and said he wants to get in front of the next wave of development. In contrast, there are some markets where Harrison does not …

FacebookTwitterLinkedinEmail
InterFace-Houston-Industrial-Design-Construction-Panel

By Taylor Williams New development within the Houston industrial market is increasingly skewing toward data centers and advanced manufacturing projects, creating new hurdles for architectural, engineering and contracting (AEC) teams to overcome in terms of labor and timing. At the annual InterFace Houston Industrial conference that took place in late August at The Briar Club and was attended by more than 200 industry professionals, Jason Cooper, president at Houston-based general contractor Arch-Con Corp., immediately cited both of these issues when asked about the biggest challenges the industry faces today. Braylie Manson, business development associate in the Houston office of Texas-based engineering firm Dunaway, moderated the conference’s design and construction panel. “The most difficult thing of the past year, excluding the past month or so, has been getting highly qualified subcontractors on board that can keep the schedules that are expected,” said Cooper. “Schedules keep accelerating; we have to turn these projects over faster and faster, so [as general contractors], we have to be very selective about which subcontractors we use to avoid delays.” Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about …

FacebookTwitterLinkedinEmail

Richmond’s retail market continues to be one of the bright spots in commercial real estate, and it’s not difficult to understand why. While many markets across the country are still working through elevated vacancies and changing consumer habits, Richmond continues to benefit from steady population growth, a diverse economy and a retail inventory that remains remarkably full. Retailers continue to expand here. Investors continue to buy here. And perhaps most importantly, consumers continue to support both national brands and local businesses in a meaningful way. The result is a market that feels healthy, active and well-positioned for future growth. Quality space is hard to find If there’s one thing everyone in can agree on today, it’s that quality retail space is increasingly difficult to find in Richmond. Vacancy throughout the region remains exceptionally low, particularly in established corridors, hovering at around 3.6 percent in the second quarter. Areas like Short Pump, Midlothian and many neighborhood shopping center locations continue to operate with very little available inventory, creating a competitive environment for retailers looking to enter the market or expand existing operations. This has caused rents to continue to trend upward, leaving the landlord with the upper hand. The interesting part …

FacebookTwitterLinkedinEmail

— By Tony Pierangeli of SRS Real Estate Partners — On the surface, Denver’s retail real estate market looks healthy. Vacancy remains low, rents have held firm and investment activity has strengthened. Industry sources reported a vacancy rate between 4 percent and 5 percent in the second quarter of 2026. The market has recently added a couple of new-to-market retailers, and grocery remains one of the most active and consistent segments. Grocery-anchored centers, convenience-oriented retail and quick-service concepts continue to expand, providing a strong foundation for the market. But the statistics don’t tell the entire story. Beneath the surface, a growing number of retailers, developers and landlords are confronted with a fundamental challenge: the economics of new retail development have become increasingly difficult to pencil. Construction costs remain elevated, municipal fees have increased, financing remains expensive, and protracted zoning and permitting processes add significant time and uncertainty to a project. Colorado’s property tax structure can also contribute to high triple-net expenses for retailers. At the same time, state and local requirements related to electrification, EV charging, composting and higher wages can add to operating and development costs, making the market less competitive for some concepts. The result is a market …

FacebookTwitterLinkedinEmail
Newer Posts