By Taylor Williams
AUSTIN, TEXAS — For more than a decade coming out of the Great Financial Crisis, the Austin growth story sold itself to the multifamily investment community, and at the height of the market, faith in that narrative alone might have been enough to sway an investment committee to tour, underwrite, offer and close.
The past several years have seen a major departure from that modus operandi, as Austin has perhaps borne an outsized share of pain and erosion of fundamentals amid the larger U.S. apartment boom. Back are the days of basis resets, granular scrutinization of line items, skepticism of below-market exit cap rates and highly bifurcated submarket performances. It’s an inverted version of the multifamily utopia that prevailed throughout the state capital in times of historically low interest rates, and to confidently buy in Austin today requires conviction that the current state of affairs is only temporary.
Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe.
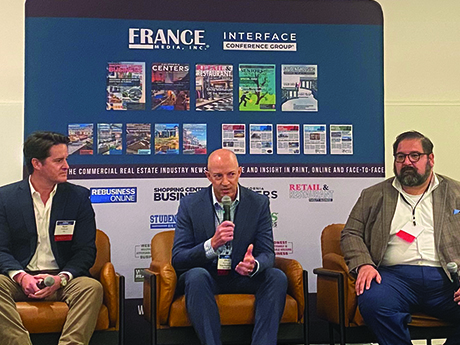
So spoke a handful of multifamily investment sales professionals at the annual InterFace Austin Multifamily conference, which took place in mid-September at the Austin Marriott Downtown hotel. Guided by moderator Brendan Lewis, vice president and Texas/Oklahoma manager for Asset Preservation Inc., a brokerage firm specializing in 1031 exchange deals, the panel vacillated between blunt acknowledgement of today’s hardships and cautious optimism for a return to pre-2022 fundamentals. Or at least pre-pandemic fundamentals, given that 2020 and 2021 were historical outliers in terms of rent growth and valuations.
Ryan McBride, director and co-lead of Central Texas multifamily business at JLL, was the first panelist to speak on the state of the Austin multifamily sector and wasted no time in describing the market as “at an inflection point.” McBride said that on paper, many multifamily buyers remain sold on Austin’s long-term fundamentals and are performing preliminary due diligence on deals in the market. But that interest has yet to translate to meaningful sales volume.
“Groups are trying to figure out where they can enter and what product type they want to have in this market, which is moving quickly but also viewed as in a dip right now,” McBride said. “But it’s a strong time to invest, and groups that can see the vision and have conviction in where Austin is going will be able to make some pretty compelling bets.”
McBride checked that point shortly thereafter by conceding that the recent runup in the 10-Year Treasury yield, which eclipsed 5 percent for the first time since 2007 in September, had injected the market with a fresh source of anxiety. He also acknowledged that groupthink mentalities — as evidenced by the accepted narrative that Central Texas is in a multifamily slump — contributed to the slow rebound in deal volume, and that the latest activity with the 10-Year only exacerbated those notions.
“When trends change like with the 10-Year, that’s a quick reason [for potential buyers] to point out why they can pay less for a property, and rightfully so in some cases,” McBride said. “In other instances, that creates opportunities to lean in. So while we’re trying to absorb what’s happened over the past couple weeks, our thesis on Austin remains strong in the long run, but we need some stabilization in the short run for underwriting to make any kind of sense.”
Zar Haro, executive vice president at Colliers’ Austin office, concurred that the broader narrative surrounding multifamily fundamentals in the Austin market is not great at the moment. Haro similarly noted that smart buying opportunities do still exist against that backdrop, though less so for groups that had recently pulled the trigger on new acquisitions.
“There’s a difference today between an apartment market and an apartment deal,” Haro said. “The apartment market is in disarray as relates to Central Texas, but the apartment deal that actually trades in Central Texas is probably one of the better basis resets. And that’s the theme of today: basis reset. The other theme is ‘nothing but upside’ — the belief that people will keep moving here and absorb these empty units, and we’ll see a return to rent growth.”
Patton Jones, vice chairman of multifamily capital markets at Newmark’s Austin office, echoed Haro’s concerns on the supply side of the market but maintained that absorption rates are improving in real time. Jones added that the “supply hangover” in greater Austin stemmed from the delivery of about 50,000 new units over the past two years but said that with regard to the pace of absorption, his company is able to “sell that positive side of the story.”
Another panelist agreed.
“When we think about Austin over the past several years, all anybody talks about is the supply. But the absorption has been historically strong, yet is always overlooked [in the conversation],” said Chris Stutzman, managing partner at Texas Multifamily Advisors. “That’s what’s kept us in the game, and with supply growth starting to dwindle and the job and population growth remaining positive and strong, we’re seeing little green shoots start to pop up throughout various submarkets.”
Later in the discussion, multiple panelists pointed out that Austin’s sagging rents had also impacted the narrative that the state capital was no longer an affordable place to live — this time for the better. That notion plays into the premise that while buying in Austin today is still a bit of a gamble based on current metrics, the long-term fundamentals are there.
“If we aren’t having affordability issues, it’s justifiable to think that rents are 10 to 15 or maybe even 20 percent off where they should be, though it differs by class [of product],” said McBride. “People believe in the vision of Austin; we just don’t have the data behind it yet on these pro formas.”
“Among deals that are trading right now, we’re seeing rents that are as much as 30 percent below peak,” added J.R. Ellis, senior managing director in Greysteel’s Austin office. “It’s hard to pin down true cap rates in this market, so for guidance, we look at what buyers are underwriting in terms of exit caps. Until a couple weeks ago [when the 10-Year spiked], most groups were relatively flat on five-year exit caps. We’re seeing a lot of suburban Class A trades with in-place, 4 percent cap rates, so most of these buyers are betting on a rental recovery in the short term.”
The panel agreed that, unsurprisingly, in the absence of hard real-time data that shows improvement in fundamentals, institutional buyers have pulled back from Central Texas. Haro said those groups are currently more focused on markets like New York City, Los Angeles, San Francisco and Washington, D.C., that have “an easy thesis for upside.”