

By Matthew Wurtzebach, Draper and Kramer Inc.
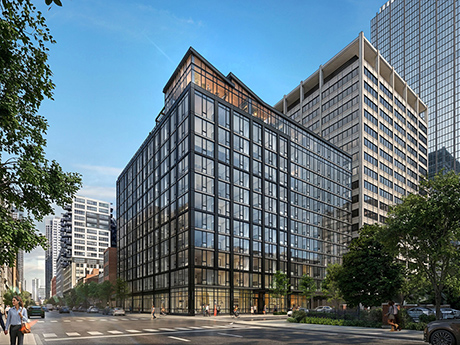
Investors who only read national headlines about Chicago are missing an important reality that local players know and national players have rediscovered: Downtown Chicago and its adjacent submarkets are one of the strongest growth stories in multifamily.
Enduring strengths
Chicago has long been known for its enduring, generational strengths. It is the nation’s transportation and logistics juggernaut, with six of the country’s seven Class I railroads, a convergence of interstate highways that provide truly national connectivity, and O’Hare International Airport, which World Business Chicago ranks as the nation’s No. 1 port by trade value, handling $423 billion in goods each year.
Chicago ranks second in the country for Fortune 500 headquarters (30), produces more than 150,000 college graduates annually, is home to world-class academic and research institutions, and boasts 21 Michelin-starred restaurants.
Given all this, it should come as little to no surprise that Chicago has ranked No. 1 for corporate expansion and relocation for 13 consecutive years per Site Selection magazine and has been named Condé Nast Traveler’s best big city in the U.S. for a decade.
Growth story
These characteristics have continued to attract and retain educated, high-earning talent with a preference for renting in proximity to both employment and entertainment.
According to Claritas, the core downtown population grew 10.4 percent between 2020 and 2026, and Fulton Market grew 9.8 percent — both more than three times the national rate. And both areas are projected to grow another 6 percent over the next five years. These residents are affluent, with median household incomes between $140,000 and $150,000 and average incomes drifting above $200,000.
Demand for more supply
Amid this backdrop, construction is only pacing demand. Claritas projects households in these submarkets will grow by more than 6,700, or 6 percent, through 2030. Against that, 2025 saw eight multifamily starts of 50 units or more downtown and in adjacent areas, totaling about 1,400 units, and 2026 has had seven starts totaling 1,900 units through September, representing only about a 3 percent increase to inventory. Integra Realty Resources projects no more than 3,000 new apartments will deliver downtown from 2025 through 2027, with new projects constrained by the availability of limited partner equity.
With nearly 90 percent of households made up of one or two people, new units have broadly tracked household formation, and the market has absorbed them: Vacancy is roughly 5 percent, and new deliveries are leasing quickly with minimal concessions.
The result has been pressure on rents. Some submarkets have posted 8 percent year-over-year rent growth, and while that trajectory is moderating, downtown is still seeing 4 percent growth. Average asking rents across all unit types in downtown Class A product are approaching $4 per square foot, with studios exceeding $5 per square foot.
Tax incentives soften risk
Despite its strengths, Chicago Class A multifamily trades at cap rates 50 to 75 basis points wider than other major markets such as Boston, Dallas, Miami and San Francisco, according to CBRE’s first-half 2026 Cap Rate Survey. Chicago often prices more in line with Cleveland and Milwaukee. Over the past decade, we have seen both debt and equity reduce exposure to Chicago in general, and Cook County specifically.
One reason for that caution among investors has been concern around real estate tax growth. In our experience, taxes have climbed from 11 percent of effective gross income to 17 percent during the past 10 years. But the Cook County Affordable Housing Special Assessment Program (AHSAP), implemented in 2021, is now serving as a release valve to address the real estate tax challenge, in addition to housing affordability.
In exchange for reserving at least 15 percent of units as affordable at 60 percent of area median income (AMI), owners receive a 25 percent reduction in assessed value for 10 years, renewable for two additional 10-year periods. For new construction downtown and in designated low-affordability areas, projects that reserve 20 percent of units at 60 percent of AMI can elect a 30-year incentive that reduces the increase in assessed value by 100 percent for the first three years, gradually stepping down to 20 percent for years 13 through 30.
Prior to 2021, developers fully absorbed the resulting net operating income hit. Today, on a typical new-construction project, we find the tax reduction offsets nearly 100 percent of the revenue lost to affordable rents while cushioning the project from future real estate tax increases. This is a very important change, and one that is helping more projects pencil out.
Capital markets execution
Currently, we are experiencing a modest pick-up in multifamily starts, made possible by broad availability of debt and growing interest from equity investors. Despite the increased cost of capital, debt liquidity remains deep. Banks, life companies, debt funds, CMBS and agency lenders are all fiercely competing for multifamily.
For top assets and borrowers, we have seen permanent loan spreads as tight as sub T+100 at moderate leverage levels, nonrecourse. At max leverage, we have found capital at T+185 with leverage limited to the lesser of 75 percent loan-to-value ratio, a 1.2 debt coverage ratio on an interest-only basis, or a 7 percent debt yield — nonrecourse, full-term interest-only.
For cash-flowing assets that need more seasoning before a sale or a permanent loan, best-in-class pricing for large middle-market and institutional projects is SOFR+200 to 225, sized to a 6.5 percent debt yield on an as-is basis, nonrecourse. Sub-$40 million loans and assets still in lease-up can price 50 to 75 basis points wider depending on the asset specifics.
Chicago’s challenges are real, as they are for every major metro. But citywide headlines obscure pockets of significant opportunity. Downtown and Fulton Market, as well as the adjacent neighborhoods, tell a different story.
Investors who have looked through the noise are earning a meaningful yield premium relative to those who followed the herd. For investors and lenders evaluating Chicago, opportunity is found in following the submarket demographics and understanding the property tax incentive. Existing owners should know that the debt market remains deep and that there is likely a capital solution to the dollars your project needs, despite the increase in rates, if you cast a wide enough net.
Matthew Wurtzebach is a senior vice president with the commercial finance group of Draper and Kramer Inc. This article originally appeared in the October 2026 issue of Heartland Real Estate Business magazine.