Content Partner

Patrick Strake Franklin Street multifamily Texas quote

Major multifamily markets in Texas, beleaguered by an onslaught of supply as developers chased new renters moving to the state during the COVID pandemic, are beginning to see signs of recovery. But it’s one that looks dramatically different not only between cities, but also from one submarket to the next. Rents are roughly flat in Dallas and remain below year-ago levels in Austin, Houston and San Antonio after two to three years of decline, says Patrick Strake, managing director with Franklin Street. And depending on the submarket, apartment renters are jockeying for, and receiving, significant concession packages relative to the rest of the United States, he adds. According to the Federal Reserve Bank of Dallas, those include six to eight weeks of free rent (and as much as 10 to 12 weeks in some submarkets). “Texas is still going to be a great spot for capital for years to come, given its job growth and business-friendly nature,” adds Strake, who is based in Austin and leads Team Texas, the firm’s statewide multifamily investment sales platform. “But right now, equity is being highly selective, because the four big metros are coming out of a supply wave on four different timelines.” Hardest …
FacebookTwitterLinkedinEmail

After three years of new construction outpacing tenant demand in many sectors and areas, commercial real estate posted a mostly encouraging report card in the third quarter of 2026. Lee & Associates’ 2026 Q3 North America Market Report shows industrial demand nearly doubled from the second quarter, while retail and multifamily extended their rebounds. Office, the sector that had been staging a comeback, slipped back into negative tenant demand territory. Sponsored: Download Lee & Associates’ 2026 Q3 North America Market Report.  Industrial Overview: Tenant Growth Gains in United States There has been broad general improvement across North American industrial markets, with demand for space rebounding in the United States. Third-quarter net absorption totaled 84,081,618 square feet, as more users gradually have set aside tariff and trade concerns that have hobbled tenant expansion since 2023. The third-quarter gains are an 89 percent improvement from 44.4 million square feet in the second quarter and a year-on-year jump of 172 percent. The third quarter’s growth brought the year-to-date total to 161.2 million square feet as net absorption has recovered from three years of tepid growth. Despite the increase so far this year, tenant expansion continues to fall short of absorbing the volume of deliveries that …

FacebookTwitterLinkedinEmail
Justin Wheeler Berkadia quote

Berkadia recently partnered with the Chen Institute for Global Real Estate Finance at NYU Stern School of Business for the third annual Multifamily Investment Case Competition, held October 15–16. The competition brought together graduate student teams from leading business schools across the country to explore how technology can enhance investment returns in the multifamily sector. Participants were challenged to develop strategies at the intersection of apartment operations, technology and innovation financing — areas that do not often converge in traditional business school curricula. “Berkadia was honored to partner with NYU Stern for the third year in a row, highlighting our commitment to supporting young professionals and future leaders in real estate,” said Justin Wheeler, Berkadia’s CEO. “Engaging with eager, thoughtful participants and judges with deep expertise in the multifamily industry was both exciting and inspiring. This event was made possible by the dedication of university teams, fellow judges and NYU’s sustained support.” This year’s competition included teams from NYU Stern, Columbia Business School, UCLA Anderson, the University of Wisconsin–Madison’s School of Business, the University of Florida Warrington College of Business and the University of Texas at Austin McCombs School of Business. An accomplished group of industry leaders served as judges, …

FacebookTwitterLinkedinEmail
The office sector showed its strongest performance since COVID in the second quarter of 2026, according to the Lee & Associates’ 2026 Q2 North America Market Report.

The Lee & Associates’ 2026 Q2 North America Market Report finds that commercial real estate fundamentals are improving, but the pace of recovery varies significantly by property type and market. Office and retail sectors are showing renewed momentum, industrial demand continues to recover unevenly amid trade uncertainty and multifamily fundamentals are stabilizing as new supply begins to moderate. Across all sectors, investors and occupiers remain highly selective in an evolving market. Sponsored: Download Lee & Associates’ 2026 Q2 North America Market Report. Industrial Overview: Recovering Demand Is Uneven Amid Trade Tensions Demand for North American industrial space in the second quarter continued to recover from slowing caused by heightened trade uncertainties that began early last year. Modest tenant expansion in the United States remains well off pre-COVID average growth. In the United States, 44.4 million square feet of net absorption in the second quarter brought the mid-year total to 77.1 million square feet, about 30 percent less than the pre-pandemic five-year average. First-half deliveries fell to 93 million square feet, which included 44.4 million square feet in the first quarter — the least in seven years. Although supply additions have moderated, the pullback in tenant demand over the past three years …

FacebookTwitterLinkedinEmail
Regions Ann Atkins Multifamily July

By Ann Atkinson, Regions Real Estate Capital Markets Midway through 2026, the multifamily industry appears to be holding steady. By many accounts, fundamentals are weathering uncertainties across the economy, job markets and geopolitical arenas. While some key metrics have softened, the overall health of the apartments sector demonstrates how essential this class of real estate is. Simply stated, everyone needs a safe place to call home. Sustained demand for rental units remains central to the sector’s health, and conditions in the for-sale market continue to shape that demand directly. For many households, homeownership has become increasingly out of reach. Affordability has eroded sharply over the past decade, driven by land use restrictions, constrained housing supply and a widening gap between mortgage costs and income, according to an October Goldman Sachs’ U.S. outlook for housing supply and affordability. Elevated interest rates in recent years have only added to the strain. Together, these factors are keeping many Americans in rentals far longer than they might have planned. Even with strong demand, the apartments market isn’t without challenges. The industry is still working through the surge in new unit supply that hit the market over the past few years. As a result, rents …

FacebookTwitterLinkedinEmail
The growing presence of first-time and out-of-market buyers throughout Texas suggests that investor confidence is beginning to return.

For much of the past several years, Texas commercial real estate markets have been characterized by a disconnect between buyer expectations and seller pricing. As interest rates increased and capital became more selective, transaction activity slowed while many property owners remained reluctant to adjust valuations. Today, that dynamic is changing. Across Texas, commercial real estate markets are undergoing a period of recalibration. While conditions vary by asset class and market, pricing expectations, capital availability and investor sentiment are gradually moving toward a new equilibrium. As that process unfolds, transaction activity is increasing and new opportunities are emerging for investors willing to take a long-term view. Transaction Activity is Beginning to Accelerate One of the clearest signs of improving market conditions is the return of transaction activity. As buyers and sellers become more aligned on pricing, more assets are trading and a broader range of investors are entering the market. Local investors remain active, while out-of-state capital continues to target Texas opportunities. In addition, many first-time buyers are pursuing acquisitions in markets and asset classes that may have seemed out of reach during previous market cycles. This increase in participation is helping restore liquidity and creating a healthier transaction environment. Rather …

FacebookTwitterLinkedinEmail
Michael Glass, Marcus & Millichap

For much of the past several years, commercial real estate investors have navigated a market defined by uncertainty. Interest rate volatility, inflation concerns, geopolitical tensions and shifting workplace trends have all contributed to an environment where predicting the next move can feel increasingly difficult. Against that backdrop, the Midwest continues to stand out for a different reason: stability. Across many Midwest markets, commercial real estate fundamentals have remained relatively balanced compared with other regions of the country. While some markets have experienced dramatic swings in pricing, development activity and occupancy levels, much of the Midwest has maintained a steadier trajectory. That consistency allows investors and operators to focus on executing long-term business plans rather than constantly reacting to market volatility. Stability Remains the Midwest’s Competitive Advantage One of the region’s greatest strengths is the balance between supply and demand. Unlike certain Sun Belt markets that have experienced significant waves of new development, many Midwest metros have avoided substantial oversupply. As a result, property owners have been able to continue implementing value-add strategies, improving operations and generating steady rent growth. Commercial real estate success is rarely built overnight. In many Midwest markets, returns are generated through disciplined management, operational efficiencies and …

FacebookTwitterLinkedinEmail
The owners who will come through the process successfully, are the ones who are proactive, realistic, and have a clear plan, whether they are refinancing, selling or bringing in a capital partner. — Ann Atkinson, Managing Director of Real Estate Capital Markets, Regions Bank

The mass of multifamily loan maturities that has peaked over the past few years remains elevated and is destined to impact the industry in 2026. Coupled with current elevated interest rates, and what accompanies them, these loans pose challenges to owners faced with the need to refinance. These hurdles are proving too difficult for some owners who secured their current property loans during the record low-interest rate period several years ago and who are now over-levered. While the maturity wall did subside a bit in 2025, that doesn’t mean the 2026 volume of maturities isn’t sizable. According to the Mortgage Bankers Association 2025 Commercial Real Estate Survey of Loan Maturity Volumes, 13 percent of mortgages backed by multifamily properties will mature in 2026 — a wave that will inarguably lead to a surge in transaction activity, whether successful refinances or forced sales. How We Got Here Interest rates in the United States reached an all-time record low during the 2020 – 2021 period. Many apartment owners capitalized on the inexpensive cost of debt and financed their properties for extremely low rates. However, in the years since, the country has battled serious bouts of inflation which, in turn, have caused the …

FacebookTwitterLinkedinEmail
Retail page of Lee & Associates Q1 2026 North America Market Report

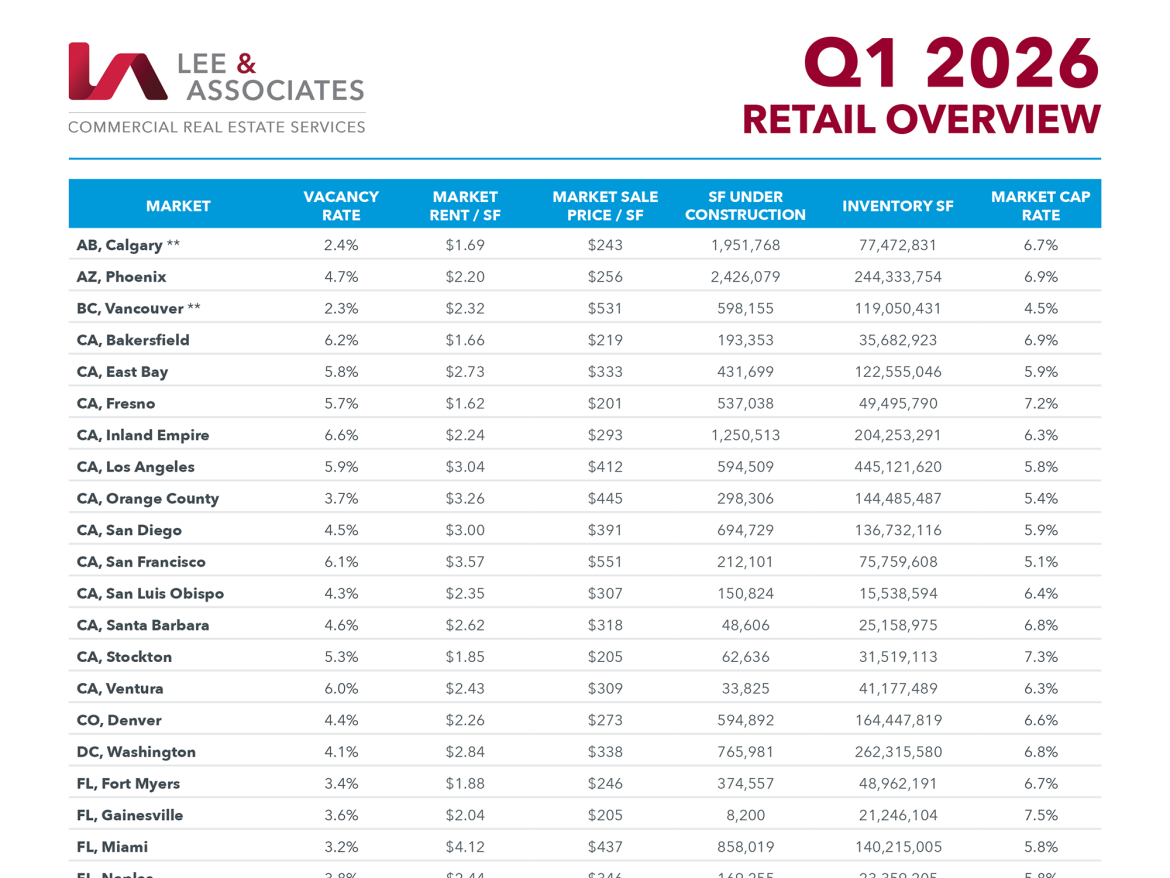
The headline numbers in commercial real estate rarely tell the full story. First-quarter 2026 data is a case in point: Lee & Associates reports that industrial and multifamily are slowly absorbing a historic supply surge, office is staging an uneven recovery, and retail is contending with a shortage of quality space rather than a glut of it. Here’s a sector-by-sector look at where U.S. commercial real estate stands heading into the rest of the year — and which markets are bucking the trend. Sponsored: Download Lee & Associates’ 2026 Q1 North America Market report. Industrial Overview: Logistics Demand Moderates; Small Space Needs Gain There was continued weakness in the first quarter across North American industrial markets. The slowing has produced an overhang of newly delivered speculative logistics space, while rent growth has fallen to virtually nil. In the United States, net absorption totaled 32.8 million square feet in Q1, or 0.2 percent of the 19.3-billion-square-foot inventory. It was the lowest rate of tenant growth in more than a decade aside from the 17.6-million-square-foot contraction in Q2 following the U.S.’s initial tariff announcements. The overall vacancy rate in Q1 settled at 7.5 percent, which has nearly doubled since 2022 as new …

FacebookTwitterLinkedinEmail
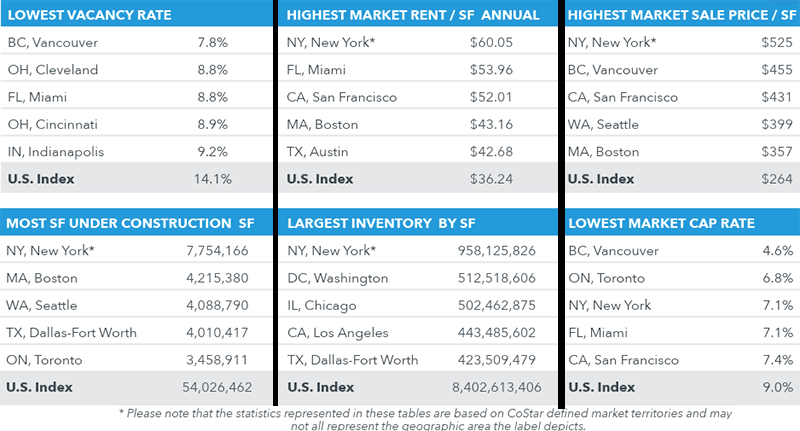
These tables highlight major office market indicators across North America for Q42025, including vacancy rates, rents, prices per square foot, construction activity, inventory sizes and capitalization rates. Source: Lee & Associates’ 2025 Q4 North America Market Report.

Lee & Associates’ 2025 Q4 North America Market Report looks at diverging market demand across industrial, office, retail and multifamily spaces nationwide in the last quarter. Demand continued to soften for industrial spaces, while multifamily saw a reversal: decreased demand after seven consecutive quarters of strengthening. Office saw a slow increase in net absorption, but only after six years of negative absorption; retail demand was mixed. Industrial and retail spaces contended with tariff concerns, while all four types of commercial real estate saw either decreased or slowed rent growth in the final quarter of 2025. Lee & Associates’ full, detailed market report is available to read here. The overviews for the sectors below illustrate the market landscape through data on net absorption, leasing and development activity, sales transactions and rent growth, in addition to demand. Industrial Overview: Demand Falls Under Tariff Pressure Falling demand for industrial space continued in 2025 under the added strain of the United States’ aggressive trade and tariff policies affecting commercial property markets across North America. In the United States net absorption declined again in 2025 as tenant and rent growth fell to their lowest levels since the aftermath of the financial crisis. Meanwhile, inventory growth has been scaled back …

FacebookTwitterLinkedinEmail
Newer Posts