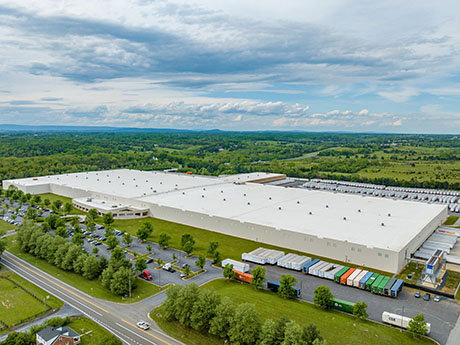
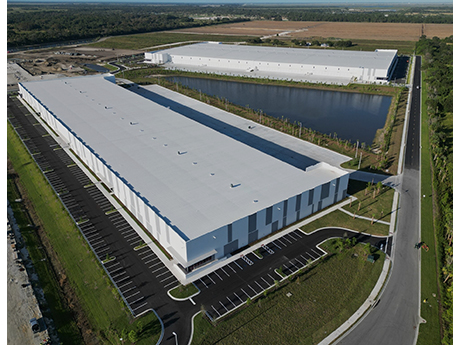
STUART, FLORIDA — JLL Capital Markets has arranged a $66.8 million loan to refinance South Florida Gateway, a 987,184-square-foot industrial development located at 2400-2450 Southwest Gateway Place in Stuart, a coastal city about 40 miles north of West Palm Beach. Melissa Rose, Michael DiCosimo, Michael Romero and Nicole Diaz of JLL secured the floating-rate loan on behalf of the borrowers, Orlando-based Foundry Commercial and San Francisco-based Stockbridge Capital Group. The lender was not disclosed. South Florida Gateway comprises two newly delivered buildings that are situated on nearly 65 acres. Building One features 285,510 square feet of rear-load warehouse space with 32-foot clear heights, 60 dock doors and two drive-in ramps. Building Two encompasses 701,674 square feet of cross-dock distribution space with 36-foot clear heights, 120 dock doors and four drive-in ramps.
Loans
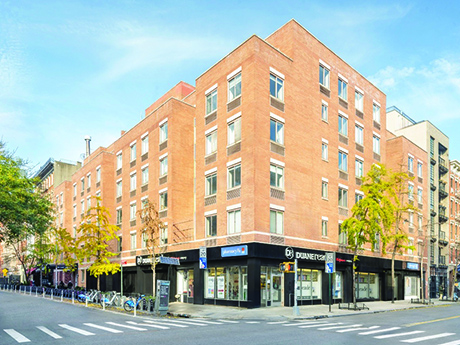
NEW YORK CITY — Locally based owner-operator Benchmark Real Estate Group has received a $44.5 million loan for the refinancing of a 61-unit apartment building located at 194 E. Second St. in Manhattan’s East Village. The six-story building offers a fitness center, resident lounge and landscaped courtyard in addition to 15,450 square feet of retail space that is anchored by convenience store operator Duane Reade. Michael Zaremski, John Flynn and Clayton Ross of JLL arranged the loan through Citi on behalf of Benchmark, which purchased the building in 2024 and implemented capital improvements.
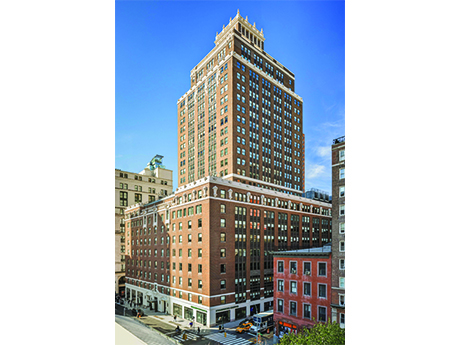
NEW YORK CITY — New York Life Insurance has provided a $386 million loan for the refinancing of 200 Madison Avenue, a 750,000-square-foot office building in Midtown Manhattan. The 26-story building was originally constructed in 1926. Havas Health is the building’s anchor tenant via a 15-year, 254,118-square-foot lease extension and expansion that was signed in August. Other tenants include architecture practice Spectorgroup and boutique law firm BraunHagey & Borden. Jonathan Estreich, Peter Duncan and Egor Petrov of Estreich & Co., along with Adam Spies, Adam Doneger and Willis Robbins of Newmark, arranged the five-year, floating-rate loan. The borrower, George Comfort & Sons, owns the building in partnership with Loeb Partners Realty and Jamestown.
Stockman Development Receives $482.5M in Financing for Ski Resort in Steamboat Springs, Colorado
by Amy Works
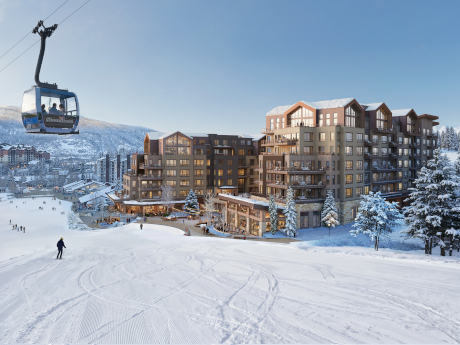
STEAMBOAT SPRINGS, COLO. — Stockman Development, led by Marquee Development, has secured $482.5 million in financing from GoldenTree Asset Management to advance The Stockman, Auberge Collection, which recently broke ground at the base of Steamboat Resort in Steamboat Springs. The financing comes amid early residential demand for the project, with more than 25 percent of residences under contract since sales launched earlier this summer. The early sales includes four of the project’s rooftop Barn residences, including a $19 million residence. The Stockman, Auberge Collection will include 95 ski-in, ski-out private residences and a 59-key Auberge Collection hotel. Amenities will include culinary venues, slope-side après, a full-service Wellbeing by Auberge spa and pool, ski valet and year-round programming. Located at 1965 Ski Time Square Drive, the nine-story property will offer the only luxury branded ski-in, ski-out residences in Steamboat Springs. The hotel and residences are slated to open simultaneously in 2030. The Stockman development marks Marquee Development’s expansion into the mountain sector. The Chicago-based developer is known for creating mixed-use destinations anchored by sports and entertainment.
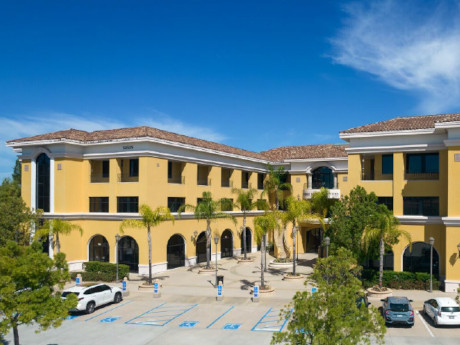
TEMECULA, CALIF. — Gantry has secured a $9 million life company loan to retire a CMBS loan on Vail Ranch Town Square, a low-rise office building in Temecula. Tony Kaufmann, Toby Judge and Jake Davis of Gantry represented the borrower, a Southern California-based private real estate investor, in the financing. Gantry will service the fixed-rate, three-year loan for the lender. Located at 32605 Temecula Parkway, the three-story, 55,000-square-foot building is fully leased to a variety of medical, dental, behavioral health and professional service tenants.
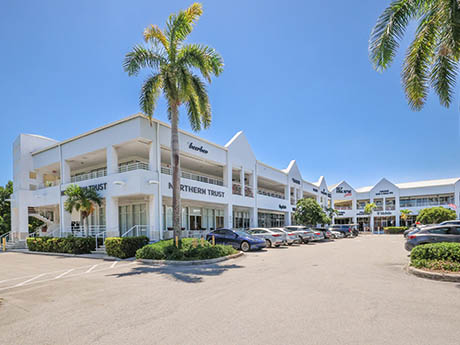
KEY BISCAYNE, FLA. — Berkadia has arranged a $9.8 million loan to refinance a 61,504-square-foot, two-story retail center located on Key Biscayne, a barrier island situated south of Miami. Charles Foschini, Christopher Apone, Shannon Wilson and Lourdes Carranza-Alvarez of Berkadia secured the 10-year, fixed-rate loan through a correspondent life insurance company on behalf of the undisclosed owner, which purchased the property in 1997. The financing features a 23 percent loan-to-value ratio. The retail property is situated on Crandon Boulevard, Key Biscayne’s primary commercial corridor and its only land connection to mainland Miami. Built in 1990, the center was 98.8 percent leased at the time of sale to a mix of tenants such as T-Mobile and Northern Trust.
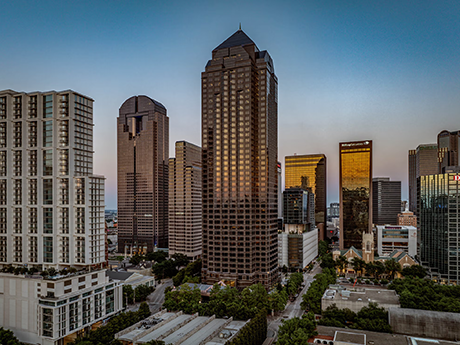
DALLAS — JLL Capital Markets has arranged $406 million in CMBS financing for Trammell Crow Center, a more than 1.2 million-square-foot trophy office tower located in the Arts District of downtown Dallas. Greg Napper, Jordan Buck and Rett Daugbjerg of JLL secured the five-year, fixed-rate, single-asset single-borrower (SASB) loan through Wells Fargo and Morgan Stanley on behalf of Regent Properties LLC. Delivered in 1985, Trammell Crow Center rises 50 stories and is 92 percent leased to a mix of major tenants such as Goldman Sachs, Baker & Botts LLP, Vinson & Elkins LLP, Orix and Prudential, among others. In 2019, the property underwent a $185 million redevelopment completed by the previous owner, JPMorgan Asset Management. Renovations included the construction of a new parking structure, a complete lobby overhaul and the addition of 27,000 square feet of ground-floor retail, as well as a full suite of amenities like the TCC Athletic Club, a conference center, an outdoor pavilion and on-site dining options. Regent Properties acquired Trammell Crow Center in March 2022 for an estimated $600 million, according to several media sources. The company has owned, operated or sponsored more than $4 billion in real estate transactions, spanning 12 million square feet of …
BUFFALO, N.Y. — Locally based financial intermediary Largo Capital has placed a $24 million permanent loan for a 300,000-square-foot industrial property in Buffalo. The address of the property was not disclosed, but the site is located within an “established” industrial park just south of the downtown area. The property was fully leased to a single tenant at the time of the loan closing. Jack Phillips of Largo Capital arranged the nonrecourse loan through an undisclosed CMBS lender. The borrower was also not disclosed.
IPA Arranges Joint Venture Equity for Cliff at Green Valley Ranch Adaptive Reuse Project in Henderson, Nevada
by Amy Works
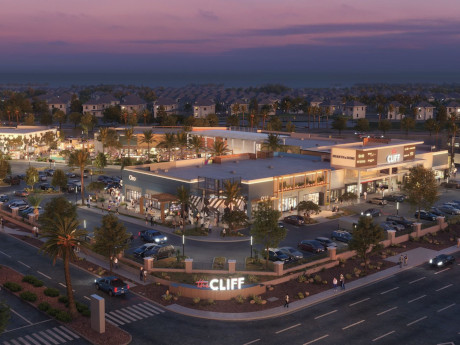
HENDERSON, NEV. — IPA Capital Markets, a division of Marcus & Milichap, has arranged joint venture equity on behalf of VAC Development for The Cliff at Green Valley Ranch, an adaptive reuse redevelopment in Henderson. Jeremy Slocumb of IPA Capital Markets led the transaction. Upon completion, The Cliff at Green Valley Ranch will be Henderson’s first major open-air retail, dining and lifestyle development of its scale since 2004. The project will convert two obsolete office buildings, built in 2002 on 10 elevated acres at 2500-2550 Paseo Verde Parkway, into a 100,000-square-foot, Class A, pedestrian-friendly campus. The Cliff will feature 38 units ranging from 200-square-foot kiosks to a 16,000-square-foot Arhaus anchor, all organized around a 26,000-square-foot covered outdoor dining lounge. The project will emphasize experiential retail, chef-driven dining, wellness, art and community gathering space. Confirmed tenants include The Taco Stand, Lyte House, Barista Botanist and Killer Whale Creamery. Planned amenities include landscaped courtyards and breezeways, a central bar and outdoor lounge, covered patios, a food-kiosk alley, a children’s play area, public art and live music and performance zones. Deliveries will begin in second-quarter 2027, with first tenants opening in the second half of the year.
CHESAPEAKE, VA. — Family Dollar has received $455.7 million in financing for its national distribution center portfolio, which totals 7.1 million square feet across eight properties. Wells Fargo led the group that provided the floating-rate debt, which will be used to refinance existing loans. An entity doing business as 1959 RE Holdings LLC, which acquired Family Dollar from Dollar Tree Inc. in 2025, is the borrower. The organization is a Delaware limited liability company that is controlled and partially owned by affiliates of Brigade Capital Management and Macellum Capital Management, Virginia-based Family Dollar occupies the entirety of the portfolio on a long-term, triple-net master lease. The distribution network serves roughly 7,100 Family Dollar retail stores nationwide. Family Dollar has maintained operations at the properties for an average of 22 years. Built between 1997 and 2013, the facilities range in size from 832,000 to 907,000 square feet, with clear heights ranging from 30 to 42 feet. The portfolio benefits from access to major transportation corridors, and each distribution center is within reach of more than 123 million people within a 12-hour drive, on average. Christopher Peck, Christopher Pratt and Alex Staikos of JLL Capital Markets led the debt origination efforts on …
Newer Posts