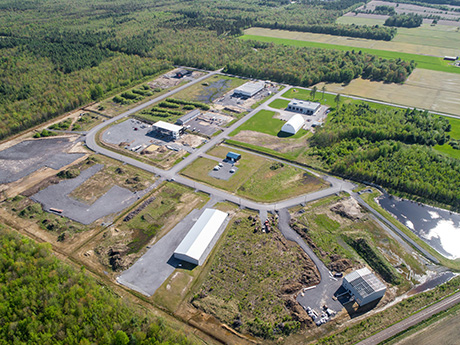
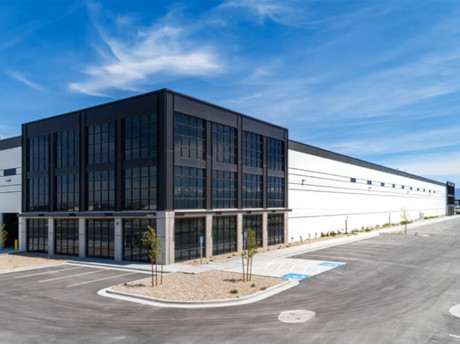
SALT LAKE CITY — Jones Lang LaSalle Securities (JLLS), a member of JLL Capital Markets, has structured and placed a $112 million credit tenant lease and equipment financing for a newly completed industrial facility located at 6320 W. 300 South in Salt Lake City. JLLS served as placement agent for the developer, Riverbend Management. The lease financing and tenant improvements loan was structured to mature with the initial lease term and provide the borrower a single source of financing at a competitive, long-term, fixed rate. The loan allowed Riverbend Management to refinance an existing construction loan in addition to funding more than $80 million of equipment manufacturing improvements. Following tenant improvements, Riverbend will convert the 309,489-square-foot industrial property into a manufacturing facility. Bill Cavagnaro and Austin Johnson of JLLS represented the borrower in the financing. Additionally, JLL Work Dynamics represented the tenant on selection of the manufacturing site, and JLL Project and Development Services served as construction monitor.
Loans
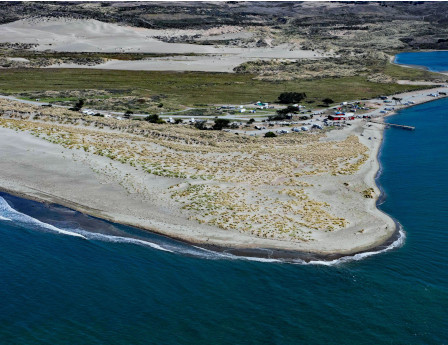
DILLON BEACH, CALIF. — PACE Loan Group has arranged a $4.4 million commercial property assessed clean energy (C-PACE) loan secured by a special assessment for Lawson’s Landing, a RV resort and campground in Dillon Beach, approximately 60 miles northwest of San Francisco. The loan will support the nearly 70-year-old campground’s new wastewater treatment, solar energy and efficiency improvements. The improvements will facilitate and enhance new restrooms and rental cottages at the 608-acre property. C-PACE is a tool that can finance energy efficiency and renewable energy improvements on commercial property. The family-owned and -operated campground features 311 RV and tent sites and a general store. The planned upgrades include installation of a wastewater management system, which will support 20 new cottages and additional restrooms with hot showers. The addition of the wastewater project will eliminate emission-intensive septic waste removal by truck and create operational cost savings of approximately $1.1 million per year. Slated for completion by December, the project received approval from the California Coastal Commission in April 2020. The campground has already completed a new 5,000-square-foot barn, which used part of the C-PACE financing to add a 76.7 kW Photovoltaic system to partially offset the property’s operating energy requirements.
NEW YORK CITY — New Jersey-based intermediary Cronheim Mortgage has arranged a $15.4 million loan for the refinancing of the Hampton Inn Manhattan/Downtown-Financial District. The pet-friendly, recently renovated hotel has 81 rooms and offers amenities such as a fitness center, business center and complimentary breakfast. David Turley led the Cronheim team that arranged the loan through an undisclosed national bank on behalf of the borrower, Virginia-based Shamin Hotels.
AcquisitionsContent PartnerDevelopmentFeaturesIndustrialLee & AssociatesLoansMidwestMultifamilyNortheastOfficeRetailSoutheastTexasWestern
Property Owners Recalibrate Expectations Following Financing Challenge, Shifting Vacancy Rates
High costs, modulating occupancies and a lack of financing options reshaped the industrial, office, retail and multifamily sectors in the fourth quarter of 2023, signaling the determining factors for 2024, according to Lee & Associates’ 2023 Q4 North America Market Report. The industrial sector saw stabilizing tenant demand — the number of new buildings delivered increased in the fourth quarter, while new construction starts slowed. Meanwhile, the office sector’s struggles deepened as more than half of the office leases signed pre-2020 approach their expiration by 2026. With low-rate loans maturing into a high-rate environment, the factors troubling the office sector seem insurmountable in this decade. In the retail market, low vacancies did not lead to booming construction in that sector in the last quarter of 2023 — financing costs plus land and labor costs have hampered new development in spite of high demand. Finally, the health of multifamily markets is tied closely to geography. Sun Belt multifamily properties and their Midwest and Northeastern market counterparts are seeing reversals from the multifamily trends of 2021: formerly fast-growing Sun Belt markets are experiencing slowed rent growth or rent decline, while rent growth for slower-growing, major North and Midwestern metros has grown steadily. Lee & Associates …
BROWNSVILLE, TEXAS — BridgeCore has provided an acquisition loan of an undisclosed amount for an unnamed, 60-unit multifamily property in the South Texas city of Brownsville. The loan carries a two-year term with a six-month extension option and a 67 percent loan-to-value ratio. The undisclosed borrower, which acquired the property via a 1031 exchange, will use a portion of the proceeds to fund capital improvements.
Berta Management Secures $18.5M Financing for Delray Corner Shopping Center in South Florida
by John Nelson
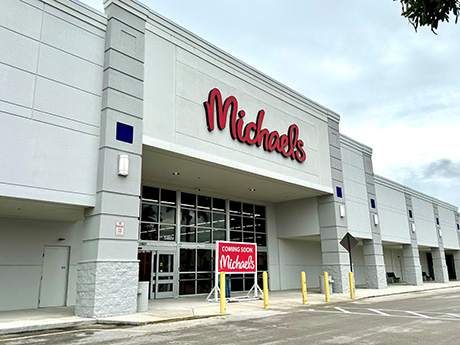
DELRAY BEACH, FLA. — Berta Management has secured an $18.5 million loan for the refinancing of Delray Corner, a shopping center located at 14802 S. Military Trail in Delray Beach. Justin Neelis of Concord Summit Capital arranged the five-year, fixed-rate financing on behalf of the borrower. The South Florida retail center comprises 86,043 square feet of leasable space. Michaels is scheduled to open a 25,600-square-foot store in the first quarter of this year as the new anchor tenant, taking over a renovated space formerly occupied by Bed Bath & Beyond. Other tenants at the property include Conviva, CVS/pharmacy and Starbucks Coffee.
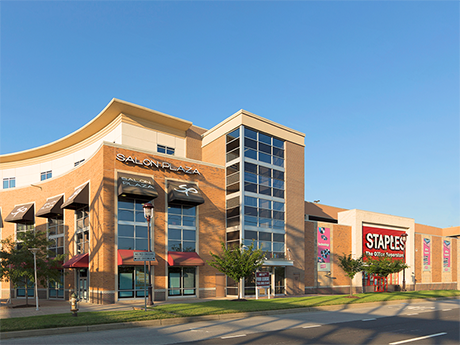
HYATTSVILLE, MD. — JLL Capital Markets has arranged an $18.4 million loan to finance the acquisition of Metro Shops, a retail center located in the Washington, D.C., suburb of Hyattsville. Michael Klein, Max Custer, Brian Buglione and Benjamin Morgenthal of JLL secured the financing through Loews Corp. on behalf of the borrower, Northpath Investments. Built in 2007 at 2900 Belcrest Center Drive, Metro Shops totals 160,623 square feet and is situated across from the 1 million-square-foot Mall at Prince George’s. Tenants at the center include Bob’s Discount Furniture, Staples, LA Fitness, Dunkin’ and Citibank.
SHERMAN, TEXAS — New York City-based Lument has provided an $11.3 million Freddie Mac loan for the refinancing of Easton Parc Apartments, a 232-unit multifamily property located in the North Texas city of Sherman. Built in 1986 and renovated in 2013, the garden-style property consists of 22 buildings on nearly nine acres. Amenities include a pool, clubhouse, dog park and onsite laundry facilities. Sloan Stevens of Lument originated the 10-year loan, which is structured with five years of interest-only payments and a 30-year amortization schedule. The borrower was not disclosed.
ELMONT, N.Y. — The Feil Organization has refinanced Home Depot Shopping Center, a 269,490-square-foot property located at 600 Hempstead Turnpike in the Long Island community of Elmont. Feil has owned the property since 1992. At the time of the loan closing, the center was fully leased, with Marshalls and Target serving as the other anchor tenants. Estreich & Co. arranged the $23.5 million loan for the refinancing through Principal Asset Management on behalf of Feil.
Ariel Property Advisors Arranges $5.5M Refinancing for Guadalupe Plaza Retail Center in Albuquerque
by Amy Works
ALBUQUERQUE, N.M. — Ariel Property Advisors has arranged a $5.5 million cash-out refinancing for Guadalupe Plaza, a shopping center in Albuquerque. The grocery-anchored plaza features 87,000 square feet of retail space. Matt Swerdlow, Matthew Dzbanek and Rhea Vivek of Ariel Property’s Capital Services Group secured the financing for the borrower, a New Jersey-based investor. The 15-year loan includes one year of interest-only payments and a 30-year amortization schedule at a 75 percent loan-to-value ratio with no prepayment penalty.