

Supply constraint has been the story of the greater New Orleans industrial market for the past seven to 10 years. Institutional capital is reluctant to develop new projects in smaller markets, despite national demand trends. In 2026, it seems as if the story is being rewritten by science fiction writers who are focused on a future of AI and space travel. In the near term, brokers and owners still face limited Class A inventory and single-digit vacancy rates. The longer view shows Louisiana’s natural resources attracting significant investment, including SpaceX’s Starbase, Louisiana in Vermilion Parish, North Louisiana’s hyperscaler data center build-out and river corridor manufacturing and port milestones driving logistics, contractor and staging demand across South Louisiana. National trends of high borrowing costs, elevated construction pricing and high insurance premiums continue to keep speculative builds rare and expansions slow. Triple-net rental rates are in the range of $8 to $12 per foot across South Louisiana markets, with newer product easily garnering the higher end of the scale as tenants have few modern options as only a handful of developers have been willing to invest capital to build speculatively in these markets to take advantage of the supply/demand disconnect. Against …
Over the past two decades, the multifamily sector, both nationally and locally, has had relatively calm seas, expanding demand, low predictable interest rates and, in the case of metropolitan New Orleans, significant barriers to entry. As a result, the headwinds that New Orleans has faced have been primarily due to national factors (interest rates, inflation) as opposed to any significant local factors. The metro New Orleans market is holding up surprisingly well despite some challenges. Demand is strong, new supply is restrained and although rent growth has been flat, occupancy remains relatively stable. Metro New Orleans is reporting overall occupancy in the 91 to 95 percent range. Average rents are $1,325 per month, with the highest being reported in Downtown New Orleans and St. Tammany Parish. It should be noted that the actual occupancy is at least 100 basis points higher as the metro has a significant number of units off-line as they undergo major renovations. The highest reported rents are in the Central Business District (CBD)/Warehouse District, which consists of predominately mid- and high-rise developments. Rents average $1,985 per month, with reported occupancy in the 92 to 94 percent range. The Mid-City market is reporting average monthly rents of …
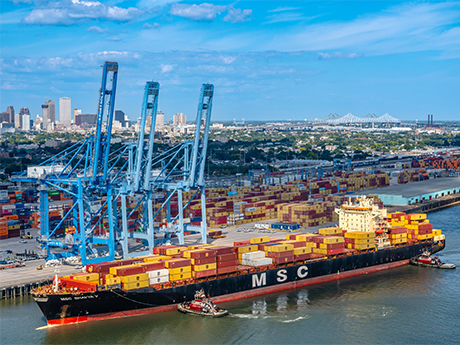
In 2022, the Port of New Orleans (Port NOLA) announced the Louisiana International Terminal (LIT), a new $1.8 billion container terminal coming to Violet, a small city about 10 miles downriver (or south) from New Orleans in St. Bernard Parish. The project is a public-private partnership between Port NOLA and two private maritime industry leaders, Ports America and Terminal Investment Ltd., and is being funded with private capital and public funding from the State of Louisiana and federal sources. The U.S. Army Corps. of Engineers is managing LIT’s environmental review and permitting process, after which the public-private partnership will begin construction. Set for completion in 2028, the ambitious project is expected to generate 18,000 new jobs by 2050 and handle 2 million TEUs (twenty-foot equivalent units) of cargo traffic annually. “I consider it the most important project in the entire region,” says Andrew Marcus, founder of local commercial real estate services firm Agile Coast. “From an economic development perspective and from a quality-of-life perspective, it is the single-most important project for our region, period. The LIT is going to be the beachhead for getting modernized containerized cargo ships to come in, and we have the ability to have several terminals …
The Greater New Orleans industrial real estate market in 2025 is characterized by steady but cautious demand, where a persistent lack of new supply continues to limit product availability and constrain tenant options despite a user base that shows signs of wanting to grow. While local prospects for business are good, tenants seem to be keeping a wary eye on national economic trends. Interest rates have increased borrowing costs, prompting tenants to delay expansions and relocations as they navigate tighter budgets. Decision making is further slowed by uncertainty surrounding potential tariffs and their possible effects on material costs that could ripple through supply chains. High insurance premiums in a region affected by hurricanes force operators to reallocate funds from growth initiatives to coverage. Construction costs remain elevated; combined with a scarcity of viable development sites, speculative builds are extremely rare, which keeps inventory tight. These headwinds, some of which should sound familiar in other markets around the country, have slowed deal velocity, though there are projects in the works that can build momentum in South Louisiana. The $1.8 billion Louisiana International Terminal (LIT) in St. Bernard Parish, a public-private partnership with Ports America and Terminal Investment Ltd., begins construction in …
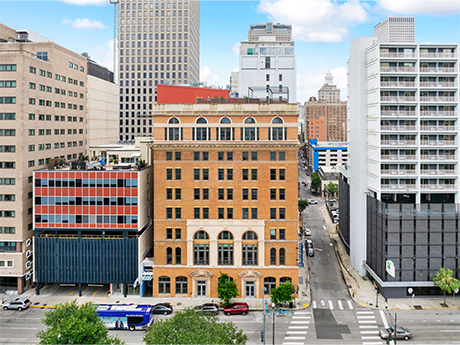
One cannot talk about, analyze, nor understand the New Orleans Central Business District (CBD) office market without a corresponding discussion of the entire CBD, not just the office building submarket. This is especially true when we look at the evolution of the New Orleans CBD since the late 1980s, and, more specifically to this article, since Hurricane Katrina. The New Orleans CBD office market is still the largest office submarket in this region. The submarket contains approximately 10.3 million rentable square feet. The balance of our submarkets (East Metairie, West Metairie, Kenner, Elmwood, West Bank, New Orleans East and the Northshore) contain a total of 8.6 million rentable square feet. More importantly, the CBD remains home for most of New Orleans’ “corporate” tenants, virtually all the region’s major law firms and financial institutions. That is the good news. However, the CBD has been transformed over the past 30+ years — and especially for the past two decades after Hurricane Katrina — from a traditional office-centric CBD to a mixed-use downtown area. The supply of office space in the CBD has shrunk from 70 buildings and 16.5 million rentable square feet in 1991, to 50 buildings and 13.8 million rentable square …
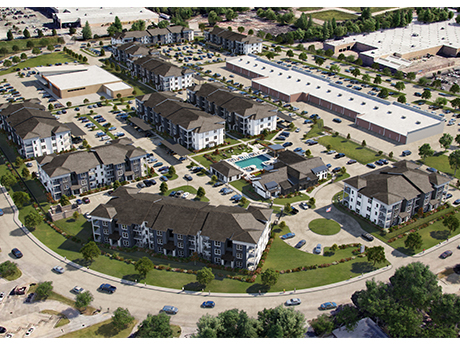
August 29, 2005 — a day no New Orleanian will forget: Hurricane Katrina. It has been two decades since the levees were breached and flood waters took over the city’s streets, homes and businesses. It was an event that changed the trajectory of the city of New Orleans. Twenty years later and the resiliency of New Orleans to always push on is evidenced by the stability of our multifamily market. Through a period of demolition, renovation and rebuilding, the overall market remains stable. The barriers to entry in the Metro New Orleans multifamily market are significant, and today as in the past, the equilibrium between supply and demand remains in sync. Like other Sun Belt markets, insurance premiums, interest rates and affordability are factors. However, they have not been a deterrent to the viability of the market or interest from investors and the capital markets. Our inventory of more than 55,000 units (professionally managed) spread out over seven parishes, remains strong. Overall metro occupancy is being reported between 92 to 94 percent with average rents of $1,300 per month. Parish by parish Eastern New Orleans and Algiers, which each have an inventory of approximately 4,000 units, offers the most affordable …
In our state of the market overview article in Southeast Real Estate Business October 2023, we defined three challenges in the metro New Orleans multifamily market. These are interest rates, inflation and insurance — or as we dubbed them “the three I’s.” Not to be redundant; however, a year later these elements are still very much factors in the current market and continue to define how multifamily assets are acquired, sold, financed and developed. There is, however, reason for optimism as each of these defining elements has diminished, albeit not completely, from where they were 12 months ago. Interest rates — On Sept. 18, the Federal Reserve reduced short-term rates by 50 basis points — the first reduction in four years. More importantly was the decline in the rate of the 10-year Treasury yield, which is what most multifamily loans are priced from. As of this writing, the 10-year Treasury yield was at 3.76 percent, the lowest it has been in the past 16 months. A further reason for optimism is the fact that the Fed has indicated the potential for four rate cuts next year. There is also the anticipation of further clarity in the capital markets once the …

Despite healthy local market dynamics, the greater New Orleans industrial market did not perform as strongly as insiders expected it to perform over the past 12 months, which is indicative of wider economic factors suppressing a market with pent-up demand. The Port of New Orleans and its access to major shipping routes along the Mississippi River has long been the principal component for industrial real estate in the area. The recent 2024 regular session of the Louisiana Legislature committed $230.5 million to Port of New Orleans infrastructure projects, including allocations to the Louisiana International Terminal, a $1.8 billion project in Violet, La., scheduled to be operational in 2028, which will be the Gulf South’s premier container shipping gateway able to accommodate New Panamax- and Post New Panamax-sized vessels. A bit further up the Mississippi River but still in the greater New Orleans region, Canadian company Woodland Biofuels announced a $1.35 billion investment at the Port of South Louisiana in Reserve, La., to establish the largest renewable natural gas plant in the world. The facility will take waste wood and sugar cane and turn it into natural gas. The process will be carbon-negative, leaving less carbon in the atmosphere than before …
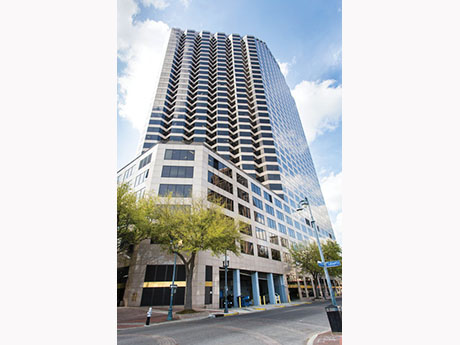
A combination of short sales, declining occupancy rates, loan concerns and migration to suburban offices contribute to uncertainty in the New Orleans office market. As we approach the fourth quarter of this year and begin to reflect back on the market in 2024, the challenges unfortunately outweigh the opportunities. Two notable cases include The DXC Technology Center and The Energy Centre. The DXC Technology Center, located at 1615 Poydras St. in the Central Business District (CBD), a once-prized office tower anchored by Freeport McMoRan, sold for less than $37 per square foot. The building, over 500,000 square feet, traded for $18.5 million, significantly below the remaining debt on the property. The New Orleans Police Department recently signed a lease to occupy approximately 45,000 square feet in the building, which lessens the steep decline in the building’s value. The Energy Centre, located at 1100 Poydras St., is one of the most desirable and best-performing Class A towers in the CBD. It entered receivership, but the building is back on track and is rumored to be nearing a sale. The building owner, The Hertz Group, controls four additional Class A office towers on Poydras St. (400, 650, 701 & 909 Poydras St.), …
For the past decade, the inventory of industrial space in the Greater New Orleans market has not been large enough to meet demand. Comprising mostly older product that would be considered Class B or C in more populous markets, New Orleans-area warehouses have an overall vacancy rate of less than 2 percent. The demand has resulted in rising rental rates. Development of new product is warranted, but a combination of factors has prevented new projects from being built. Finally, in 2023, despite increased construction costs, high insurance costs and rising interest rates, projects are underway that will accommodate the demand in a market that is long overdue for new, modern warehouse product. Despite having all the ingredients to be a major industrial market, including one of the country’s largest port systems, warehouse infrastructure in New Orleans is dated, mostly due to a lack of suitable land for development. Institutional ownership and investment here is limited to select groups that, while chasing higher yields, took the time to learn the market’s dynamics and build local relationships. Historically, as brokers and tenants bemoaned a lack of product, national developers were reluctant to deploy capital to speculate in an unfamiliar and unproven locale. …
Newer Posts