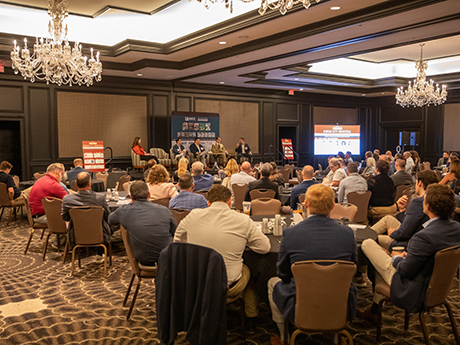
For industrial developers and owners, Kansas City is an easy sales pitch right now. “Two years ago, we had to scrounge around [for capital partners] trying to get phone calls returned. Now, they’re calling us saying they’re ready to see what we’ve got,” said Nick Cook, a development manager with Panattoni Development Co. “You’re always trying to sell a story to these folks. And Kansas City is a pretty easy one to sell right now. When it comes to speculative development, we’re feeling bullish.” Cook’s remarks came during the developers, owners and investors panel at the InterFace Kansas City Industrial conference, which took place Tuesday, Aug. 18 at the Intercontinental Kansas City at the Plaza. Robert Ciston, a senior principal with BRR Architecture, moderated the discussion. Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe. Fellow panelist Grant Harrison, executive vice president of development with VanTrust Real Estate, also expressed a bullish mindset on Kansas City and said he wants to get in front of the next wave of development. In contrast, there are some markets where Harrison does not …
Midwest Market Reports
Conference CoverageIndustrialKansasMarket ReportsMidwestMidwest Market ReportsMissouriMultifamilyRetail
By Scott Olson As I look back over the last 12 months since my August 2025 Cedar Rapids update, the resilience of this city to adapt despite high interest rates, tariffs and a Middle East conflict is second to none. Our city council priorities have remained unchanged: • Housing options and affordability • Strengthen and stabilize neighborhoods • Clean and safe city • Recreational and cultural amenities • Homelessness • Flood control system The economic growth highlighted in this report is matched by city efforts in all the priority areas. Our current national rankings reflect these successes: • No. 3 Best Place to Live in the Midwest (SpaceWise, 2026) • No. 3 City with the Most Affordable Rent (WalletHub, 2026) • No. 5 Midwest City for a Peaceful Retirement (lnvestopedia, 2026) • No. 11 Most Affordable Small City to Buy a Home (WalletHub, 2026) • No. 16 Best City to Buy a House in America (Niche.com, 2026) • No. 19 Safest City in Americas (WalletHub, 2026) — ranked across key dimensions, including home and community safety and natural disaster risk and financial safety • No. 22 Best Run City in the U.S. (WalletHub, 2025) • No. 30 City with the …
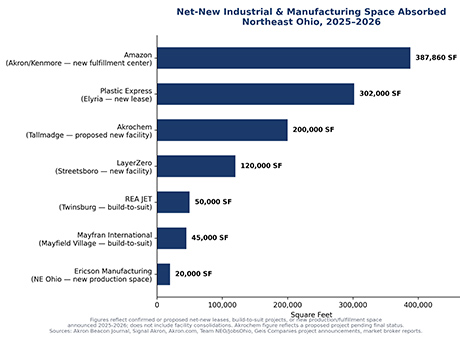
By Troy Gerspacher, Gerspacher Real Estate Group/CORFAC International After five straight quarters of tenants giving back more space than they took, Northeast Ohio’s industrial market is finally turning a corner. The reason isn’t a sudden rush of new demand. It’s that almost nobody built anything speculative for two straight years, so the modest leasing activity we’re seeing is enough to move the needle. A manufacturing market Northeast Ohio has never been a mega-warehouse market chasing Amazon-style fulfillment. We’re a manufacturing region. Most of the active deals are in buildings under 100,000 square feet run by regional manufacturers and smaller operators who have been here for decades. Deals aren’t driven by national logistics players making their way in because of population growth. Instead, deals are driven by suppliers to the region’s manufacturing base. Market data tells the story Data sources all point to the same fact: Cleveland’s industrial market remains very tight. Vacancy stood at 4.3 percent in the first quarter of 2026, with average asking rents around $6.70 per square foot, according to CoStar. That’s particularly notable compared with the national industrial vacancy rate, which started the year at approximately 7.5 percent. The market also recorded approximately 420,000 square …
By Kevin Malinowski, Colliers | Cleveland-Akron Greater Cleveland continues to strengthen its position as one of the Midwest’s most competitive business and commercial real estate markets with Ohio’s recognition as CNBC’s No. 1 “State for Business in 2026,” a distinction driven by strong infrastructure, competitive operating costs, strategic market access and a growing supply of development-ready sites. Those advantages are translating into corporate investment, job creation, real estate activity and public-private partnerships across Northeast Ohio. High-profile investments are helping fuel the region’s momentum. According to reports, Cleveland Clinic is investing more than $1 billion in healthcare, research and innovation initiatives, including construction of its new Neurological Institute on its main campus. Nearby, Canon Healthcare USA acquired a building near Cleveland Clinic’s main campus for its U.S. headquarters and operations. Sherwin-Williams recently completed its new downtown headquarters and suburban research campus. The project is widely regarded as one of the largest corporate investments in the city’s history and reflects the company’s continued presence and investment in the region. Like many other downtown office markets, Cleveland’s office sector is evolving as companies optimize workspace needs. That said, Cleveland has emerged as a notable leader for converting office to residential with projects such as …
By Tony Avendt, Cushman & Wakefield At first glance, Detroit’s industrial real estate market appears to be entering a period of moderation. Vacancy has crept upward, new supply continues to trickle online and recent quarters have posted negative absorption. Yet beneath these headline indicators lies a more complex — and arguably more resilient — story. The numbers alone do not fully capture how tenant behavior, shifting supply dynamics and a growing pool of “shadow space” are reshaping the market in subtle but meaningful ways. As of the first quarter of 2026, metro Detroit’s industrial vacancy rate stood at 4.1 percent, marking the 11th consecutive quarterly increase and the highest level since 2015. Even so, the market remains significantly tighter than the national average of approximately 7 percent, reinforcing Detroit’s position as one of the more supply-constrained industrial markets in the U.S. Rental performance tells a similarly stable story. Net average asking rents reached $7.40 per square foot in the first quarter — a 2.1 percent year-over-year increase and the highest level since late 2023. While rent growth has moderated from earlier peaks, landlords have largely maintained pricing power, particularly for well-located, modern distribution facilities. Still, the market is recalibrating after …
By John Schenk and Parker Gilmore, CBRE For two decades, Cincinnati did not see many new apartment projects built compared with its peer cities, with annual deliveries trickling along at roughly 965 units between 2000 and 2020, while merchant builders showed a preference to Columbus or Indianapolis for their predictability. But 2021 marked the beginning of a breakout period as a favorable macroeconomic backdrop, along with surging national and regional appetite, conditioned a thunderstorm of new development at the record-breaking tune of over 3,000 units per year. A combination of economic growth, demographic shifts, refreshed renter expectations and institutional capital interest has positioned Cincinnati as one of the Midwest’s most compelling multifamily investment stories as of late. The numbers tell a story of Midwestern confidence. Cincinnati recorded nearly $943 million in multifamily sales volume for 2025, representing 7,381 units traded — a dramatic increase from 2024’s $517 million and 2023’s $314 million. Blended pricing reached approximately $122,834 per unit with transaction counts on the rise as investors sought exposure to the fundamentals Cincinnati offered so well. Behind the surge in transaction activity is a fundamental shift in how developers, investors and residents are viewing the Queen City’s investment potential. A …
By Kimm Lauterbach, REDI Cincinnati Shaped by its strong German heritage, brewing tradition and historic role as the nation’s pork-processing capital, earning the nickname “Porkopolis,” the Cincinnati region has long been defined by industry, entrepreneurship and innovation. That legacy of reinvention has transformed Cincinnati into one of the Midwest’s most resilient and strategically positioned economic development markets. Anchored by a diverse economy, a central location within a one-day drive of nearly 60 percent of the U.S. population and a growing concentration of advanced industries, the region is experiencing sustained investment across industrial and life sciences. Unlike many peer markets that are dependent on a single industry, Cincinnati benefits from a balanced economic base led by advanced manufacturing, life sciences, aerospace and aviation, food and beverage and logistics. For the first quarter of 2026, REDI Cincinnati has welcomed the highest number of site visits since our inception. Industrial powerhouse Industrial real estate remains the strongest-performing commercial sector in the Cincinnati market. Cincinnati’s industrial vacancy rate stood at approximately 5.4 percent during the first quarter of 2026, according to Cushman & Wakefield, reflecting a healthy and balanced market despite significant inventory growth over the last several years. Positive absorption has continued, …
By Aaron Hyde and Justin Lossner, JLL Regional markets like Des Moines are no longer waiting their turn. Retailers and office users that once bypassed mid-sized metros for coastal or high-growth markets are compressing their timelines and arriving here ahead of schedule. Heading into the second half of 2026, that shift is already playing out on the ground. Des Moines faces constrained supply and steady demand—not excess capacity. Across retail and office, the question isn’t whether tenants want to be here, but whether growth can physically occur. Retail: strong demand Retail vacancy in metro Des Moines sits around 3.5 percent, the tightest rate in over a decade. Demand spans categories: Quick-service restaurants, banks, auto tenants, fitness and junior box soft goods retailers all absorb space as it becomes available. Retailers are no longer simply looking for the next door down the street. They’re expanding regionally, and markets like Des Moines are benefiting as larger metros tighten. National retailers now enter Des Moines earlier in their expansion cycles. In fact, roughly 36 percent of new national retail leases were signed within five months of space becoming available. Des Moines is consistent with that velocity. Space — not demand — limits growth …
By Maxx Kossof, The Missner Group Chicago’s industrial market is active — vacancy is low, rents are up and the construction pipeline remains substantial. But the market is not uniform. Smaller deals, in tighter locations and existing buildings, are moving. That segment has been underserved for some time, and that is starting to change. Big box is largely spoken for Chicago’s active construction pipeline is significant, but the majority of it is already committed. The large projects breaking ground are build-to-suit developments for specific users, including Kimberly-Clark, CJ Logistics and Walmart. Big speculative groundbreakings have been largely absent for some time, reflecting a period of softer leasing demand that is only now beginning to recover. That pipeline serves an important segment of the market, but a narrow one. Most tenants are not those users. They are regional distributors, light manufacturers and last-mile operators looking for 25,000 to 90,000 square feet in a location that works for their workforce and customers. For years, speculative development bypassed this segment in favor of larger tenants and higher absolute rents. That is beginning to shift. Infill is competitive When a well-located older building becomes available in Chicago, there is real competition for it. The …
By Ben Azulay, Bradford Allen Downtown Chicago’s office market is entering a period defined less by the disruptions of recent years and more by the opportunities taking shape in their wake. Tenants are committing or recommitting to quality space, investors are acquiring assets at more compelling valuations and office-to-residential conversions are removing obsolete supply. Leasing activity pulled back in the first quarter of 2026, with approximately 1.6 million square feet of direct deals completed, according to Bradford Allen’s first-quarter downtown Chicago office market report. That is down from just over 2 million square feet in fourth-quarter 2025. Several notable transactions reflect a market increasingly defined by location and building quality. Global food brand Mars Snacking made the quarter’s most significant commitment, signing a new 169,816-square-foot headquarters lease at Fulton Labs, 400 N. Aberdeen St. in Fulton Market, while also absorbing the 37,672-square-foot former Kellanova space in River North as part of a broader expansion that will bring more than 600 new jobs and $100 million in investment to the city. In its second expansion in the building in four years, IMC Financial Markets leased an additional 104,000 square feet at Willis Tower, bringing its total footprint there to approximately 250,000 …
Newer Posts