Market Reports

For industrial developers and owners, Kansas City is an easy sales pitch right now.  “Two years ago, we had to scrounge around [for capital partners] trying to get phone calls returned. Now, they’re calling us saying they’re ready to see what we’ve got,” said Nick Cook, a development manager with Panattoni Development Co. “You’re always trying to sell a story to these folks. And Kansas City is a pretty easy one to sell right now. When it comes to speculative development, we’re feeling bullish.”  Cook’s remarks came during the developers, owners and investors panel at the InterFace Kansas City Industrial conference, which took place Tuesday, Aug. 18 at the Intercontinental Kansas City at the Plaza. Robert Ciston, a senior principal with BRR Architecture, moderated the discussion.  Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe. Fellow panelist Grant Harrison, executive vice president of development with VanTrust Real Estate, also expressed a bullish mindset on Kansas City and said he wants to get in front of the next wave of development. In contrast, there are some markets where Harrison does not …
FacebookTwitterLinkedinEmail
InterFace-Houston-Industrial-Design-Construction-Panel

By Taylor Williams New development within the Houston industrial market is increasingly skewing toward data centers and advanced manufacturing projects, creating new hurdles for architectural, engineering and contracting (AEC) teams to overcome in terms of labor and timing. At the annual InterFace Houston Industrial conference that took place in late August at The Briar Club and was attended by more than 200 industry professionals, Jason Cooper, president at Houston-based general contractor Arch-Con Corp., immediately cited both of these issues when asked about the biggest challenges the industry faces today. Braylie Manson, business development associate in the Houston office of Texas-based engineering firm Dunaway, moderated the conference’s design and construction panel. “The most difficult thing of the past year, excluding the past month or so, has been getting highly qualified subcontractors on board that can keep the schedules that are expected,” said Cooper. “Schedules keep accelerating; we have to turn these projects over faster and faster, so [as general contractors], we have to be very selective about which subcontractors we use to avoid delays.” Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about …

FacebookTwitterLinkedinEmail

Richmond’s retail market continues to be one of the bright spots in commercial real estate, and it’s not difficult to understand why. While many markets across the country are still working through elevated vacancies and changing consumer habits, Richmond continues to benefit from steady population growth, a diverse economy and a retail inventory that remains remarkably full. Retailers continue to expand here. Investors continue to buy here. And perhaps most importantly, consumers continue to support both national brands and local businesses in a meaningful way. The result is a market that feels healthy, active and well-positioned for future growth. Quality space is hard to find If there’s one thing everyone in can agree on today, it’s that quality retail space is increasingly difficult to find in Richmond. Vacancy throughout the region remains exceptionally low, particularly in established corridors, hovering at around 3.6 percent in the second quarter. Areas like Short Pump, Midlothian and many neighborhood shopping center locations continue to operate with very little available inventory, creating a competitive environment for retailers looking to enter the market or expand existing operations. This has caused rents to continue to trend upward, leaving the landlord with the upper hand. The interesting part …

FacebookTwitterLinkedinEmail

— By Tony Pierangeli of SRS Real Estate Partners — On the surface, Denver’s retail real estate market looks healthy. Vacancy remains low, rents have held firm and investment activity has strengthened. Industry sources reported a vacancy rate between 4 percent and 5 percent in the second quarter of 2026. The market has recently added a couple of new-to-market retailers, and grocery remains one of the most active and consistent segments. Grocery-anchored centers, convenience-oriented retail and quick-service concepts continue to expand, providing a strong foundation for the market. But the statistics don’t tell the entire story. Beneath the surface, a growing number of retailers, developers and landlords are confronted with a fundamental challenge: the economics of new retail development have become increasingly difficult to pencil. Construction costs remain elevated, municipal fees have increased, financing remains expensive, and protracted zoning and permitting processes add significant time and uncertainty to a project. Colorado’s property tax structure can also contribute to high triple-net expenses for retailers. At the same time, state and local requirements related to electrification, EV charging, composting and higher wages can add to operating and development costs, making the market less competitive for some concepts. The result is a market …

FacebookTwitterLinkedinEmail
Kephart-Pull-Quote

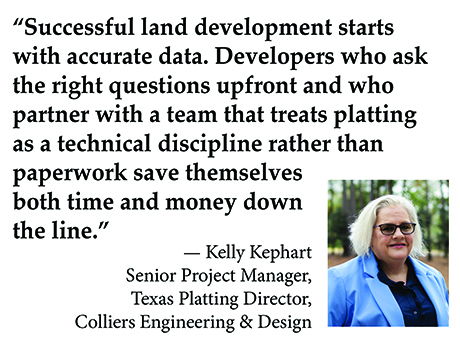
By Maria Gutierrez, senior communications specialist, Colliers Engineering & Design Whether it pertains to acquiring sites, designing improvements or developing a residential or commercial property in Texas, land terminology can quickly become confusing. Two terms that are commonly mistaken, and often used interchangeably, are survey and plat. “In this field, people often use these terms synonymously, but they fulfill completely different steps in the development process,” notes San Antonio-based Corey Campbell, RPLS, geographic discipline leader for survey and geospatial at Colliers Engineering & Design. “A survey gathers and documents the physical facts about the land on the ground, while a plat uses those facts to legally define how that land is divided and recorded for the future.” Because an approved plat depends entirely on accurate site data, a comprehensive title survey is almost always the required first step. Navigating that transition from survey to recorded plat requires a complete end-to-end strategy. That is where Kelly Kephart, senior project manager and Texas platting director for survey and geospatial services at Colliers Engineering & Design, spends her time. Based in Houston and with 26 years of experience and over 1,000 completed plats, Kephart helps developers clear regulatory hurdles and manage the entire …

FacebookTwitterLinkedinEmail

For years, Richmond occupied an interesting position in the Mid-Atlantic multifamily landscape: large enough to attract institutional capital, but often overshadowed by bigger markets such as Washington, D.C., and Northern Virginia. That is changing. Richmond has moved considerably higher on investors’ target lists over the past several years, initially propelled by the migration patterns that emerged during the pandemic. People flocked to Richmond for its relatively affordable housing and quality of life.  While that migration isn’t occurring at COVID-era levels today, those fundamentals remain. Increasingly, investors are recognizing that Richmond offers something particularly valuable in the current environment: attractive yield in a market where pricing has not necessarily caught up with the underlying fundamentals. Fundamentals hold up Richmond’s multifamily market is absorbing a meaningful amount of new supply while continuing to generate rent growth. Effective rents reached $1,658 at midyear, representing 4.1 percent growth, while occupancy stood at approximately 94 percent, according to Pyxis. The market absorbed 2,733 units over the previous 12 months, according to research from CoStar Group. Those numbers are particularly noteworthy given the recent construction cycle. Nearly 7,000 units were completed during the past 12 months. Another 5,736 are expected during the coming year, according to …

FacebookTwitterLinkedinEmail

— By Don Zebe of Colliers Idaho — more mature and geographically diverse stage of growth. While the Treasure Valley remains the state’s primary development engine, retail expansion is increasingly occurring in markets such as Twin Falls, Idaho Falls, Ammon, Rexburg, Pocatello-Chubbuck, Coeur d’Alene and Post Falls. Idaho’s population surpassed 2 million residents in 2025, providing a strong foundation for grocery, restaurant, medical, service and neighborhood-oriented retail uses. However, population growth alone no longer guarantees project success. Elevated construction and financing costs have made retailers and developers increasingly selective, placing greater emphasis on access, visibility, traffic patterns and regional drawing power. Treasure Valley Remains the Development Leader The Treasure Valley continues to receive the greatest volume of retail construction and leasing activity in Idaho. Major projects like the District at Ten Mile in Meridian reflect the growing preference for mixed-use destinations that combine retail, dining, fitness and services. The continued expansion of the Village at Meridian further demonstrates the market’s ability to attract both first-to-market and expanding national retailers. Despite ongoing development activity, the Boise-area retail market remains relatively tight, with retail vacancy at 4.4 percent in the second quarter of 2026, supporting continued demand for well-located space. Magic Valley Growth Strengthens …

FacebookTwitterLinkedinEmail
InterFace-Houston-Retail-Development-Panel

By Taylor Williams In terms of both ground-up construction and expansions and redevelopments of existing properties, retail development in the greater Houston area is pretty healthy by today’s standards, which is to say that meaningful supply gains in major markets are relatively rare in 2026. But the numbers are working in Houston, where sources say that brick-and-mortar sales are strong enough to support the rents that justify new development. Yet at the same time, margins remain thin on both the tenant and landlord sides, and owners are still very much focused on finding creative ways to manage development and operating costs lest they lose that precious, hard-fought cushion. “There’s a ton of new development around the horn, with projects in Katy, Fulshear, Tomball, Magnolia, Baytown and [New Caney’s] Valley Ranch, and those deals are penciling because retailers are keeping up with rents,” said Kenneth Katz, co-founder and principal at Houston-based brokerage firm Baker Katz. His comments were delivered at the annual InterFace Houston Retail & Mixed-Use conference at the Houston Briar Club on Aug. 25., which was attended by more than 200 industry professionals. Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial …

FacebookTwitterLinkedinEmail

If there is one thing I have learned over the past year, it’s that retail buyers have not left Orlando. They have become more selective, and that selectivity is exposing the real issue in the market: there are not enough high-quality retail properties available for sale in the trade areas investors want most. Inventory remains near all-time lows throughout Central Florida, especially in established trade areas with strong demographics, excellent visibility and limited opportunities for new development. As a result, buyer demand continues to outpace the number of available opportunities.  Orlando remains one of the strongest retail markets in the country, supported by healthy consumer spending, positive net absorption and a limited construction pipeline that continues to give investors confidence. For owners, this creates an important window. Properties with strong locations, durable tenancy and a clear growth story are standing out because buyers have fewer comparable alternatives to pursue. In this market, quality does not just protect value; it creates competition. One of the biggest changes I have noticed over the past few years is how buyers evaluate opportunities. A few years ago, investors moved much faster. Today, they spend more time underwriting acquisitions, reviewing lease structures and understanding the …

FacebookTwitterLinkedinEmail

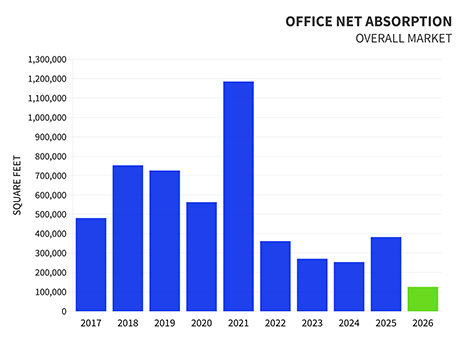
— By Patrick Shalz of TOK Commercial — Amid an office landscape that remains uneven nationally, the Boise MSA continues to distinguish itself with steady fundamentals, improving vacancy and rising rents. The market remained on solid footing through the second quarter of 2026. Overall vacancy held steady at 6.6 percent, down from 7.2 percent one year ago. It has remained remarkably consistent throughout the first half of the year, fluctuating by just one-tenth of a percentage point.  Multi-tenant vacancy also improved, declining to 10.2 percent from 10.5 percent a year earlier, reflecting continued demand for quality multi-tenant space. Overall asking lease rates reached a record high of $23 per square foot (full-service, annual), with nearly every submarket posting year-over-year rent growth. Class A asking rates also strengthened, increasing 2 percent from last year to $25.50 per square foot.  Leasing activity shifted toward larger transactions in the first half of 2026. Although the total number of office transactions declined nearly 10 percent year over year, net absorption increased 36 percent, indicating that tenants leased larger blocks of space than in the prior year. Smaller suites account for the majority of activity, but their share of the market softened with spaces of …

FacebookTwitterLinkedinEmail