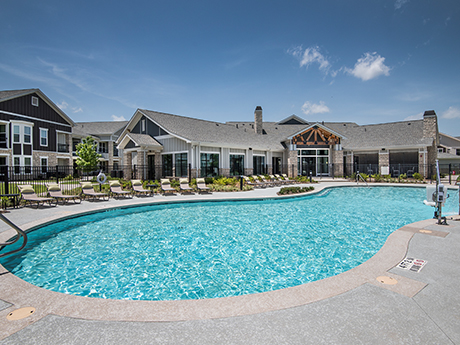
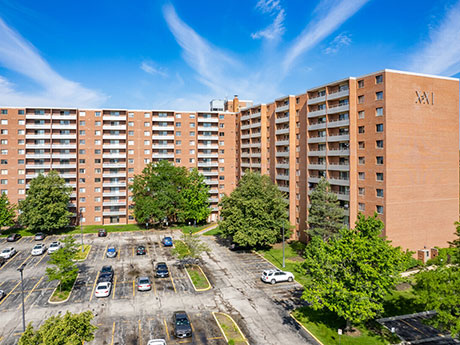
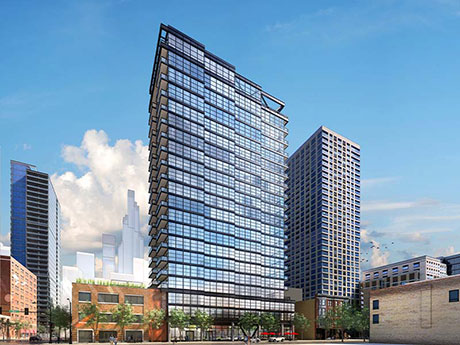
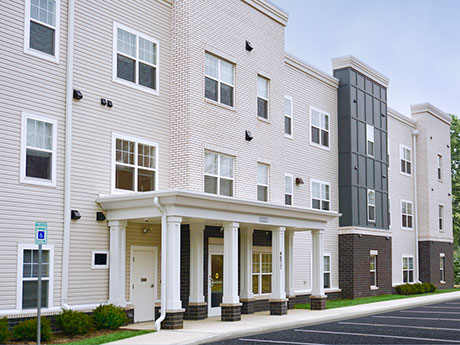
COLUMBUS, OHIO — Columbus-based developer Woda Cooper Cos. has opened Wendler Commons, a $15.4 million affordable housing development located at 4860 Wendler Blvd. in Columbus. Wendler Commons comprises 62 units that are affordable for households that earn 30 to 80 percent of area median income, including 14 one-bedroom apartments, 40 two-bedroom apartments and eight three-bedroom apartments. Four units are designed for those with mobility challenges, and two additional units are specifically equipped for those with sight and/or hearing impairments. Rental rates are $330 to $1,060 per month, depending on unit size and income restriction. Units come with cable, telephone and internet access. Community amenities include an onsite management office, a multipurpose space with a kitchenette, a playroom, a fitness center and laundry with off-street parking. The Ohio Housing Finance Agency allocated federal low-income housing tax credits to support equity financing as well as provided an equity bridge mortgage. Ohio Capital Corp. for Housing purchased the tax credits, which enabled equity financing invested by Cincinnati-based Fifth Third Bank, which also provided a construction loan. Merchants Capital provided a first permanent mortgage. The City of Columbus originated $750,000, and the Affordable Housing Trust for Columbus and Franklin County provided a primary equity bridge loan. …
Multifamily
PLATTSMOUTH, NEB. — KeyBank Community Development Lending and Investment has provided a $14.3 million construction loan for the conversion of a former high school building into affordable housing in Plattsmouth, a southern suburb of Omaha. Named Lofts on Main, the project consists of the adaptive reuse of the school as well as a ground-up building. The development will include 41 units, 32 of which will be restricted to residents who earn up to 60 percent of the area median income. Ted Witt and Samantha Yates of KeyBank structured the financing. Additionally, WNC provided $7.5 million in federal low-income housing tax credit (LIHTC) and historic tax credit funding. Advantage Capital provided $3.6 million in state LIHTC and historic tax credit funding. The Nebraska Investment Finance Authority and the City of Plattsmouth also provided funds.
By Mike Oliver, managing director, JLL Capital Markets Fundamentals remain strong within the multifamily markets of Northern New Jersey and the greater metro New York City area, though the dynamics have continued to shift since the onset of the pandemic. During COVID-19, there was movement away from urban areas toward the suburbs, creating a “tale of two cities” market dynamic. The suburban multifamily market became red-hot while urban markets cooled. Vacancies dipped below 80 percent in some instances, with heavy concessions being offered and flat to negative gross rent growth. Today, while the suburban markets remain very strong, urban markets are also now red-hot. This is attributable to more and more people heading back to urban centers in anticipation of returning to the office or simply wanting to be back in the excitement of downtown living and its dining, shopping and entertainment options. Additionally, many renters are being priced out of and fleeing Manhattan, Brooklyn and other New York City neighborhoods. Jersey City and the Hudson Waterfront provide attractive rental options with incredible access into Manhattan. Jersey City, for example, is demonstrating healthy fundamentals, as occupancy rates are back over 95 percent with strong growth on lease trade-outs. There …
Gemdale USA Receives $94.3M Construction Financing for Multifamily Development in Pleasant Hill, California
by Amy Works
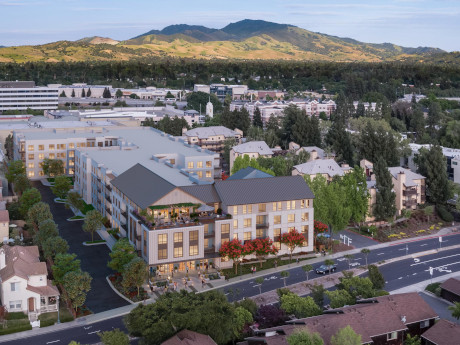
PLEASANT HILL, CALIF. — Gemdale USA has received $94.3 million in construction financing for an apartment community located in the Bay Area city of Pleasant Hill. Located at 85 Cleaveland Road, the four-story property will feature 189 apartments, a fitness center, communal lounges, clubroom, outdoor courtyard with lounge seating, amenitized rooftop and pool deck, co-working lounge, outdoor meeting rooms and fireplaces. Additionally, the property will be adjacent to 350,000 square feet of retail stores, restaurants and a movie theater. Brandon Roth, Nicco Lupo, Jordan Angel and Tatiana Hodapp of JLL Capital Markets’ Debt and Equity Advisory team arranged the senior financing through Bank OZK and the mezzanine financing through AvalonBay Communities for the borrower.
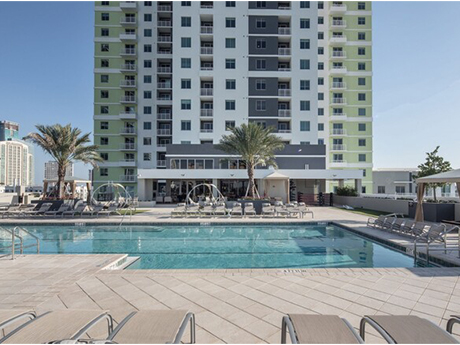
MIAMI — Affiliates of Harbor Group International (HGI), a privately owned real estate investment and management firm based in Norfolk, Va., has purchased Miro Brickell, a 372-unit multifamily property in the Brickell neighborhood of Miami. The undisclosed seller sold the asset for $184.5 million. Built in 2017, Miro Brickell features studio, one- and two-bedroom floor plans with balconies, stainless steel appliances, energy-efficient washers and dryers and modern finishes. Community amenities include outdoor electric grills, a resort-style pool with poolside cabanas, fitness center with a yoga studio, outdoor boxing gym, onsite management and maintenance, movie theater, bike storage and a dog wash station. The acquisition of Miro Brickell marks the seventh property currently under HGI’s ownership in Miami-Dade County, bringing the investor’s local portfolio to more than 1,500 units.
FUQUAY-VARINA, N.C. — Aldon, a multifamily developer and investor based in Bethesda, Md., has purchased Elevate Powell & Broad, a luxury apartment community located at 141 Stobhill Lane in the Raleigh suburb of Fuquay-Varina. The undisclosed seller traded the 384-unit community to Aldon for $129 million. Completed in 2021, Elevate Powell & Broad has been rebranded as Aldon at Powell & Broad. The property features one- and two-bedroom floorplans with stainless steel appliances, movable kitchen islands, granite countertops, private terraces and balconies, nine-foot ceilings and sunrooms in select units. Community amenities include a resort-style pool, fitness center, two dog parks, dog spa, coffee bar, game room, car care center, cornhole, playground and an outdoor pavilion with a fire pit. Aldon’s purchase of Aldon at Powell & Broad caps a trio of multifamily investments the company has made in the Research Triangle in the past 12 months totaling $315 million.
MISSOURI CITY, TEXAS — Thompson Thrift Residential, a subsidiary of Indianapolis-based investment firm Thompson Thrift, has sold The Ranch at Sienna, a 312-unit apartment community in the southwestern Houston suburb of Missouri City. Built in 2016, the property offers one-, two- and three-bedroom units averaging 1,105 square feet. Residences are furnished with private balconies and full-sized washer and dryers. Communal amenities include a pool with cabanas, a fitness center, clubhouse, coffee bar, outdoor kitchen, game room and a dog park. Houston-based Laye Capital Investments purchased the community for an undisclosed amount.
RICHMOND, TEXAS — Guefen Development Partners has acquired 13.3 acres in the southwestern Houston suburb of Richmond for the development of Haven Mission Trace, a 264-unit apartment complex. The property will consist of eight residential buildings that will house units ranging in size from 669 to 1,266 square feet, as well as a pool and a clubhouse. Ashley Casterlin of Davis Commercial represented the seller in the land deal. A tentative completion date was not disclosed.
SCHAUMBURG, ILL. — Greystone has provided a $60 million loan for the acquisition of 21 Kristin in the Chicago suburb of Schaumburg. The buyer, Bayshore Properties, is converting the 357-unit property from condos into apartments. The mid-rise building, located at 21 Kristin Drive, was originally constructed in 1980. Eric Rosenstock and Dan Sacks of Greystone originated the bridge loan, which features a two-year term and interest-only payments. Greystone will work to secure permanent Fannie Mae financing. Under the Condominium Property Act in Illinois, condo unit owners can elect to sell a property if 75 percent or more are in agreement. Sellers then have the option to either move out of their units or lease them back from the new owner.
CHICAGO — JLL has arranged $59.8 million in construction financing for 741 North Wells, a 168-unit, Class A multifamily project with 3,580 square feet of retail space in Chicago. Expected to be completed in the first quarter of 2024, 741 North Wells will rise 21 stories and include168 units at an average size of 740 square feet. Community amenities will include bike storage, a coworking lounge, rooftop pool with a sundeck and a fitness center. Christopher Knight, Mary Dooley and Medina Spiodic of JLL represented the borrower, Vista Property, in securing the four-year, floating-rate construction loan through Huntington National Bank. Skender will serve as general contractor and Antunovich Associates is the architect.