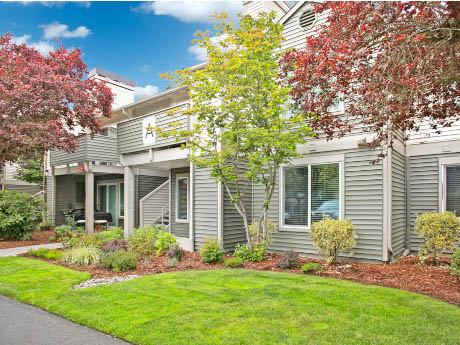
BOTHELL, WASH. — Security Properties has completed the disposition of Woodstone Apartments, a multifamily property located at 16520 North Road in the Seattle suburb of Bothell. An undisclosed buyer acquired the asset for $34.7 million. Eli Hanacek, Mark Washington, Kyle Yamamoto and Natalie Kasper of CBRE represented the seller in the deal. Built in 1989 on 6.4 acres, Woodstone Apartments features 124 one-, two- and three-bedroom units, 86 percent of which are renovated. Community amenities include a pool, spa, fitness center, playground and clubhouse.
Property Type
LOS ANGELES — BOLOUR Associates has acquired a site with three retail buildings in the Los Angeles Mid City submarket for $6 million. Located at 601, 611 and 619 S. Fairfax Ave., the buildings offer more than 11,500 square feet of net rentable area, including a former 99 Cents Only store. BOLOUR purchased the 99 Cents Only property through a bankruptcy auction after Number Holdings Inc., the parent company of 99 Cents Only Stores LLC, filed for Chapter 11 bankruptcy earlier this year and closed all of its stores. The company will renovate the three buildings to cater to gallery, design, furniture and showroom uses. In the long-term, BOLOUR plans to redevelop the site into 120 multifamily residential units. Hilco Global represented the undisclosed seller, while BOLOUR was self-represented in the deal.
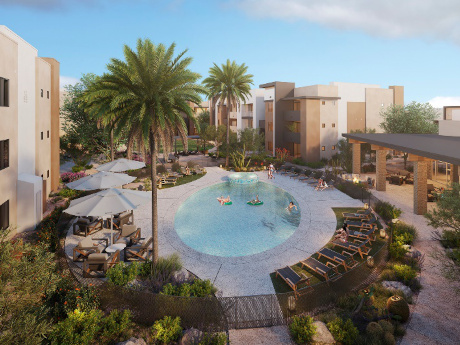
MARANA, ARIZ. — Ascent Cos. and Vanderbuild, along with Bryten Real Estate Partners as property manager, have opened Amavida Marana, an apartment community in Marana. Located at 5555 W. Ina Road, Amavida Marana features 200 one-, two- and three-bedroom units with upgraded in-home amenities including smart thermostats, nine-foot ceilings, stainless steel appliances and vinyl wood flooring. Community amenities include a private, four-acre, gated community park with four pickleball courts, a playground, a walking and jogging loop and an enclosed dog park. The property also includes electric vehicle charging stations, an indoor/outdoor fitness center, swimming pool, hot tub, pet washing stations and a clubhouse.
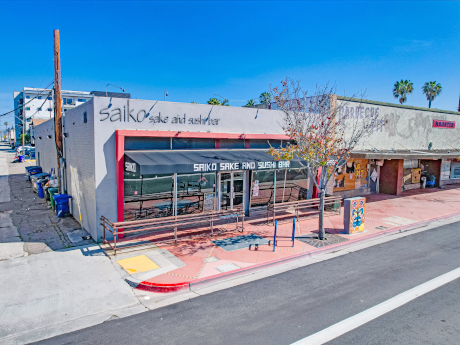
SAN DIEGO — Marcus & Millichap has arranged the sale of North Park Retail, a restaurant property at 2884 University Ave. in San Diego’s North Park neighborhood. Carlos Partners LLC sold the asset to 1295 University Family LP for $1.9 million. Built in 1948, North Park Retail features 3,200 square feet of space. The single-tenant property was renovated in 2014 for Saiko Sake and Sushi Bar’s tenant build out. After operating for 10 years, Saiko Sushi will close when its lease expires in October. The buyers plan to lease out the property after Saiko Sake and Sushi Bar’s vacates. Ross Sanchez and Nick Totah of The Totah Group of Marcus & Millichap represented the seller, while Nate Benedetto of Next Wave Commercial procured the buyer in the transaction.
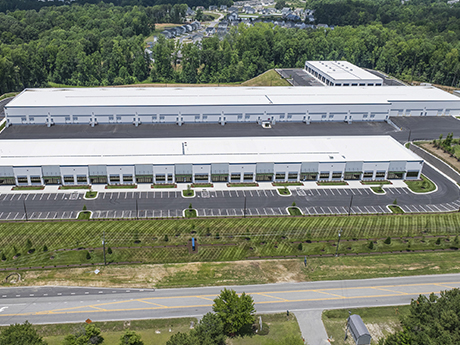
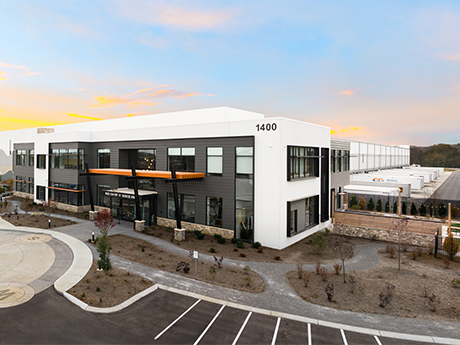
GARNER, N.C. — Merritt Properties has delivered 42 Crossing, a three-building industrial park in the Raleigh suburb of Garner that spans 213,800 square feet. Situated on 22 acres near I-40 and I-540, the park’s facilities feature 18- to 24-foot clear heights, rear-loaded docks and drive-in capabilities. 42 Crossing also offers incubator warehouses that are ideal for companies seeking 1,800 to 3,600 square feet of small-bay industrial space. These move-in ready facilities include two offices, a bathroom, a climate-controlled warehouse and at-grade drive-in access. Committed tenants at 42 Crossing include Quartz America (12,629 square feet); C. E Gandee (1,800 square feet); The Spa Haus (1,800 square feet); Choufani & Bailey Roofing (1,800 square feet); Fibrezone USA (1,800 square feet); Dock, Door, & Grille Solutions (1,800 square feet); JMO Import Automotive (1,800 square feet); Konecranes (1,800 square feet); and Pickles and Play (18,350 square feet), marking the company’s third indoor pickleball facility at a Merritt property.
Orion Acquires Net Lease Retail Portfolio Located in Florida, Texas, Illinois for $50M
by John Nelson
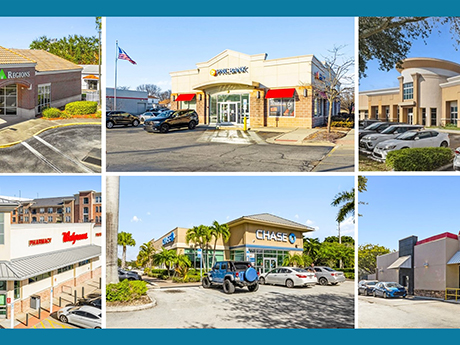
MIAMI— Florida-based Orion Real Estate Group has acquired a net lease retail portfolio located in Florida, Texas and Illinois for $50 million. An undisclosed family office sold the portfolio, which totals 94,000 square feet across 12 properties. Tenants at the portfolio — which include 11 single-tenant properties and two two-tenant properties — include banks, a fitness center, pharmacy, urgent care facility and a quick-service restaurant. The portfolio has 6.5 years of weighted average remaining lease term. Alex Sharrin, Jeff Cicurel, Eric Osika and Noel O’Donnell of JLL represented the seller in the transaction.
Greystone Provides $14.5M Agency Loan for 700 Riverchase Apartments in Hoover, Alabama
by John Nelson
HOOVER, ALA. — Greystone has provided a $14.5 million Fannie Mae loan for the refinancing of 700 Riverchase, a 216-unit apartment community located in the Birmingham suburb of Hoover. The non-recourse loan features a five-year term, fixed interest rate, interest-only payments for the full term and a 30-year amortization schedule. Rob Meehan of Greystone originated the financing, and HKS Capital Partners acted as correspondent. The borrower was not disclosed. Built in 1983, 700 Riverchase is a garden-style multifamily community with one-, two- and three-bedroom units. Amenities include a fitness center, laundry facilities, swimming pool, outdoor grill center, dog park, playground and a pickleball court.
ORLANDO, FLA. — Primark has signed a 36,000-square-foot lease at The Florida Mall in Orlando. Spanning two stories, the store will feature an entire floor dedicated to Disney merchandise. Scheduled for the end of August, the opening will bring the retailer’s U.S. portfolio to 26 locations. Primark currently operates one store in the state at Sawgrass Mills in Sunrise. Indianapolis-based Simon Property Group owns The Florida Mall, which opened in 1986.
USGBC Certifies REI Co-Op’s 400,000 SF Distribution Center Near Nashville as LEED v4 Platinum
by John Nelson
LEBANON, TENN. — The U.S. Green Building Council (USGBC) has certified REI Co-Op’s 400,000-square-foot distribution center in Lebanon as LEED v4 Platinum. Situated roughly 30 miles east of Nashville, the property is the largest LEED Platinum-certified industrial property in the Southeastern United States and one of 10 warehouses in the country to achieve LEED v4 Platinum certification, as well as the only facility in the state with that rating. Al. Neyer designed and developed the distribution center in 2023. Sustainable features of the REI distribution center include 100 percent renewable electricity via an onsite solar array, as well as a nearby solar array in east Tennessee that REI helps support; the use of reclaimed wood and metal sourced from the original barn onsite; a polished concrete stream inspired by the nearby Cumberland River; numerous skylights; and water systems to repurpose rain water. The Lebanon facility serves REI stores and customer online order fulfillment in the Midwest and Southeast, and complements REI’s three existing distribution centers in Bedford, Pa.; Goodyear, Ariz.; and Sumner, Wash. REI employs roughly 275 people at the Lebanon property, which has received industry awards from local chapters of national organizations including NAIOP and ULI.
By Taylor Williams Within the world of multifamily development, the “amenities arms race” has become a well-documented trend over the past decade, a contest to curate and deliver the most appealing combination of entertainment and wellness features and activities to woo prospective renters. In many instances, this approach was successful, and developers succeeded in capturing the hearts and wallets of renters who sought an “everything under one roof” approach to renting. The fervent movement to deliver more extensive and impressive amenity packages also worked for much of the last decade because interest rates were dirt cheap, even though costs of materials and labor needed to install these features were perpetually on the rise. But today’s market is different. Developers not only face stubbornly high construction costs, but also significantly higher interest rates. Spreads on construction loans in particular tend to be higher than on permanent loans simply because this phase of the project life cycle carries the most risk. Unlike with other asset classes such as retail and industrial, where preleasing is often a prerequisite to securing construction debt, it’s exceedingly rare for renters to commit to units that are still two-plus years away from being delivered. The absence of …