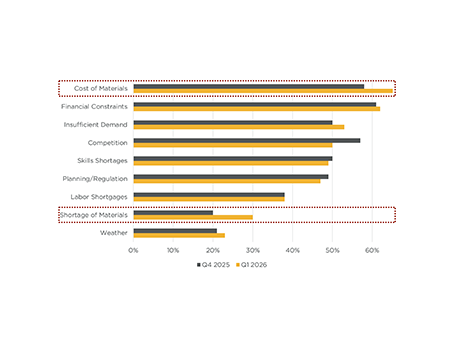
CHICAGO — As employer costs cool down, materials — particularly metals — are emerging as the bigger source of construction costs pressure, according to findings from Cushman & Wakefield’s Construction Insights: Summer 2026 report.
For much of the post-pandemic construction cycle, finding people to build was becoming increasingly expensive. Labor shortages, wage growth and competition for skilled trades pushed construction costs higher as developers navigated an already challenging development environment.
But now, that equation is beginning to change.
The recently published report shows that construction cost pressures are becoming concentrated in materials, as metals and equipment prices rise more rapidly while labor-cost growth steadies. The shift is significant for developers and contractors as the factors influencing project budgets are becoming tied to pricing commodities, which are impacted directly by tariffs and global supply chains.
The increase in commodity prices is more than 4.7 times the rate recorded a year earlier, led by aluminum at 40.9 percent, copper base scrap at 39.3 percent and nonferrous metals at 38.5 percent, as reported by Cushman & Wakefield.
A Different Kind of Pressure
According to Cushman & Wakefield, the ENR Building Cost Index rose 4.7 year-over-year in August 2026, while its skilled labor component increased 1.5 percent. Construction costs and common labor rose 3.1 percent and 1 percent, respectively.
The ENR Building Cost Index measures how the price of a fixed package of skilled labor and construction materials change over time.
Labor has not disappeared as its own challenge. The report notes that specialized trades continue to experience strain, with skilled labor costs still outpacing common labor. But compared with the pace of overall building-cost growth, wages are no longer carrying the same weight they once did. Instead, materials are filling the gap.
Overall construction materials increased 1 percent month-over-month in August, marking the third consecutive month with an increase of at least 1 percent. On an annualized basis, materials-price growth climbed from 6.5 percent in June to 8.5 percent in August, according to Cushman & Wakefield’s report.
Metals Take Center Stage
Metals have emerged as one of the clearest pressure points. Cushman & Wakefield reports that steel mill products increased 3.6 percent month-over-month in June — the largest monthly increase of 2026 at that point — even as crude oil prices fell roughly 12 percent. The report attributes the reacceleration in materials costs more closely to tariffs and metal-market dynamics than to energy prices. Meanwhile, at the broader level, metals prices increased 6.2 percent quarter-over-quarter and 36.8 percent year-over-year in the second quarter.
Copper is an especially important piece of the equation. The report cites J.P. Morgan’s estimate of a roughly 330,000-metric-ton refined copper deficit in 2026. That demand is occurring alongside structural supply constraints for copper and aluminum, creating another source of uncertainty for projects that depend on heavy metals: data centers.
A Data Center Dilemma
Demand for data center expansion is not slowing down. JLL’s Global Data Center Outlook projects nearly 100 gigawatts (GW) of new data center capacity will be added globally between 2026 and 2030. The firm expects the sector to expand at a 14 percent compound annual growth rate through the end of the decade.
In addition, Cushman & Wakefield’s 2026 Data Center Development Cost Guide puts the global data center development pipeline at nearly $2.3 trillion, further underscoring the scale and construction activity moving through the sector.
The continued expansion of data center development is especially relevant for the discussion of metals. Data centers are heavily dependent on copper for power cabling, electrical systems, cooling and data transmission, altering metal prices to be more vulnerable in the sector. Cushman & Wakefield has consistently identified data centers as one of the property types likely to feel the repercussions of tariffs because of their reliance on copper.
Power availability has also become one of the industry’s defining constraints across the United States, as more artificial intelligence (AI) and cloud demand is driving the need for additional data center capacity. This capacity requires substantial electrical and power infrastructure, and that infrastructure increases demand for materials like copper and aluminum.
The construction industry’s cost pressures are now being shaped not just by who is building, but by what the industry is building.
Tariffs Add Another Variable
Cushman & Wakefield notes that tariff impacts are increasingly flowing through to materials costs, while contractors remain cautious about passing the increase in price along to consumers.
The broader supply-chain picture offers some relief, but not necessarily enough to erase the concern. Cushman & Wakefield reports that global supply-chain pressures have eased from their April 2026 peak. However, materials costs are expected to remain elevated through the rest of the year, as new steel tariffs work their way through supply chains.
For the U.S. construction market, the result is a cost environment that is becoming much different than what we’ve previously known.
Construction costs in the United States increased 0.7 percent from the fourth quarter of 2025 through the period covered by the report, although it’s a muted increase compared with some international markets.
For example, construction costs in South Korea and Germany have increased since the end of 2025, sitting at 6.4 and 3.9 percent, respectively, as both energy and materials costs increase. Asia and Europe are expected to continue leading cost growth while conflict in the Middle East persists.
Meanwhile, Cushman & Wakefield still expects North American construction prices to accelerate as material pressures continue to circulate.
“Cost escalation is increasingly concentrated in the materials and systems that are critical to modern construction,” says Tyler Paytas, Global Head of Programs & Projects at Cushman & Wakefield. “For occupiers, early procurement, realistic budgeting and understanding where those pressures are most acute will become increasingly important as projects move forward.”
— Abby Cox