By Taylor Williams
In terms of both ground-up construction and expansions and redevelopments of existing properties, retail development in the greater Houston area is pretty healthy by today’s standards, which is to say that meaningful supply gains in major markets are relatively rare in 2026.
But the numbers are working in Houston, where sources say that brick-and-mortar sales are strong enough to support the rents that justify new development. Yet at the same time, margins remain thin on both the tenant and landlord sides, and owners are still very much focused on finding creative ways to manage development and operating costs lest they lose that precious, hard-fought cushion.
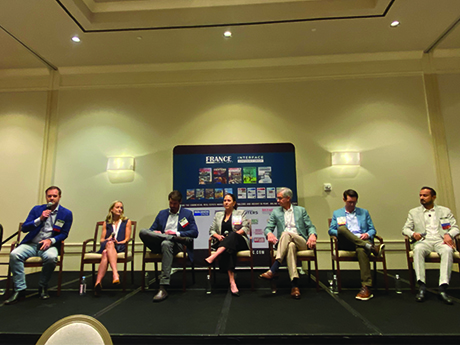
“There’s a ton of new development around the horn, with projects in Katy, Fulshear, Tomball, Magnolia, Baytown and [New Caney’s] Valley Ranch, and those deals are penciling because retailers are keeping up with rents,” said Kenneth Katz, co-founder and principal at Houston-based brokerage firm Baker Katz. His comments were delivered at the annual InterFace Houston Retail & Mixed-Use conference at the Houston Briar Club on Aug. 25., which was attended by more than 200 industry professionals.
Editor’s note: InterFace Conference Group, a division of France Media Inc., produces networking and educational conferences for commercial real estate executives. To sign up for email announcements about specific events, visit www.interfaceconferencegroup.com/subscribe.
Katz added that a key piece of the current retail environment in Houston that has enabled new retail projects and redevelopments to pencil has been a dramatic increase in rents for big-box stores. He estimated that since the pandemic, during which big boxes were among the harder-hit subcategories of retail product, rents for those spaces have “gone up by 80, 90 or even 100 percent in a lot of cases.”
The return to form for big-box stores represents a huge boost for landlords in need of anchor or junior anchor tenants that can afford healthy rents. From the perspective of the landlord of a large, multi-tenant center, having that space spoken for is a crucial prerequisite to evaluating co-tenancies and inking deals with small-shop tenants at acceptable rent levels. And according to Katz, that is more or less what’s happening right now.
“Among small-shop tenants, non-anchor retailers and restaurants, we’re seeing the same thing — rent growth is keeping up with where it needs to be to keep that development engine chugging along,” he concluded.
Moderator Craig Varney, CEO and partner at locally based general contractor Sundance Construction, echoed the notion that the anchor tenant is the first domino that has to fall to get centers flowing cash as quickly and robustly as possible.
“That’s the interesting thing about big-box development today — the economies of scale are coming back,” Varney said. “Developers are actually able to string on eight or nine tenants in a lineup now, compared to just doing a one box deal. That makes the numbers change drastically from a construction standpoint in terms of groups like us being able to design and value engineer [building] shells.”
Whereas Katz’s analysis on the volume of new retail redevelopment was mostly confined to suburbs, panelist Kevin Freels, executive vice president of investments at Midway Cos., said that the numbers are penciling on infill deals too.
“It’s a really unique period in which you can almost manufacture land in urban infill areas where historically it couldn’t be found,” said Freels. “Specifically, that means going out and finding projects with dated vintage[s] and best-of-the-best locations that have just been forgotten about but can be reimagined. If you can buy those at cheap enough bases — which you can today — and really take advantage of the infrastructure and parking that’s already there, you can really create something unique and give retailers new opportunities.”
Freels also briefly mentioned that some of these opportunities can take the form of older office campuses. Although Houston’s lack of conventional zoning would theoretically make office-to-retail conversion plays more appealing, those deals still come with massive capital outlays. And while the math is mathing for straightforward retail repositioning plays and construction costs are — according to Varney — stabilizing at the moment, the returns on office-to-retail conversions likely do not justify the risk in most cases.
Panelist Nikhil Dhanani, president of Dhanani Private Equity Group, then married two of the previous discussion threads — big boxes and redevelopment — into one piece of analysis that was also rooted in the notion that at least for now, the numbers are checking out.
“We’re looking for redevelopment opportunities,” Dhanani said unequivocally. “We did a deal in [the northern suburb of] Kingwood in which [grocer] Randalls left, and the 64,000-square-foot box was repurposed with a Trader Joe’s and Planet Fitness.” He then gave another example of a second redevelopment that spoke to the resourcefulness that owners must still exude in brick-and-mortar retail, even with the economics on their side.
“It’s a matter of getting creative, getting in front of tenants and bending over backwards [if necessary],” Dhanani said. “We sometimes see less competition on acquisitions when there are empty boxes, and although financing is not easy, we continue to see a lot of opportunities for redevelopment.”
Sasha Levine, executive vice president of Houston-based owner-operator Levcor, said that within its hometown, her company is pursuing expansions of existing retail developments like The MarqE and Post Oak Plaza. Those plays represent a sort of middle ground between ground-up construction and redevelopment, and Levine said although the numbers behind those deals are penciling, caution is still important.
“With where debt is priced today, we have to be very disciplined about what we look at and how we underwrite it,” Levine said.
Panelist Stephen Pheigaru, co-founder and managing partner at brokerage firm Palo Duro Commercial Partners, then applied the numbers-penciling theme to a different category of retail product: neighborhood strip centers. Though he struck an optimistic tone like the others, Pheigaru did not downplay the challenges that nonetheless accompany those deals.
“The challenges we see in the suburbs for unanchored shopping center start with land prices, and we’re seeing rents in those unanchored centers get to the point where some mom-and-pops are struggling to meet those numbers,” he said. “But it’s really the land prices that are the biggest challenge; construction costs and labor have stabilized.”
Panelist Kelli Drackett, senior development manager at local owner-operator Read King, then rounded out this segment of the panel by driving home the need for restraint and disciplined execution on new projects.
“Flexibility with site planning, conducting good due diligence on the front end to ensure that the site will attract an anchor, being strategic about our infrastructure — that’s what’s most important for us,” Drackett said. “We’ve got a project in which we’re looking to activate four pads, and we don’t have an anchor signed up yet. We know they’ll show up, so it’s a question of how we do that without boxing in an anchor while also establishing value within the site and starting to get that return.”