By Jeff Evans, president, Volta Global
Eight years on Wall Street, including six and a half years at long-short equity hedge funds, will teach an investor to look beyond a business’s headline characteristics. Public markets teach investors to understand business models, identify changing industry dynamics and allocate capital with attention to both opportunity and downside.
When this writer moved into private, long-term investing, that analytical discipline played an invaluable role. What changed was the horizon.
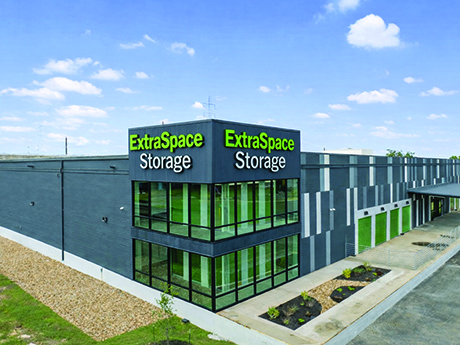
Self-storage is a core focus at Volta Global, alongside essential, unanchored strip retail centers and durable small business operations. These investments may look different, but they share a common requirement: the ability to source, underwrite, acquire and improve assets in complex, often inefficient markets.
The common thread isn’t the property type. It’s the capabilities required to create value.
How The Playbook Expanded
The decision to expand beyond self-storage was not driven by a decision to pursue another asset class. It began with an essential retail property included in a larger acquisition focused primarily on storage. Volta acquired the retail asset because it was part of the broader transaction. Once we began assessing the property, its tenants and its market, we recognized that many of the capabilities developed in self-storage applied there as well.
The sellers were different. The properties were different. But the work was familiar: assess local demand, evaluate cash-flow durability, understand competition, identify operational gaps and determine what could improve after closing. That experience changed how we assess new opportunities. Rather than asking only whether an asset class is attractive, we ask whether we have a genuine right to succeed in it.
An attractive sector is not automatically one in which every investor has an advantage. The relevant question is whether an investor’s sourcing, underwriting, operating discipline and local-market knowledge can translate to another area.
Fragmentation Creates an Edge
Self-storage is instructive because the market can be highly fragmented.
According to data from The Storage Brief, which provides research and market data for the sector, independent owners account for more than 70 percent of U.S. self-storage facilities, even as institutional ownership continues to grow — a structure that leaves substantial opportunity in smaller, locally owned assets. Individual assets are often relatively small, ownership is dispersed and transactions frequently involve owner-operators or local intermediaries.
Information can be incomplete. Reporting may be inconsistent, and operating practices may be informal. Investors often need to construct a full view of opportunities from imperfect data. That work is not glamorous, but it can create an advantage.
Repeated transactions build pattern recognition. Over time, investors learn where information tends to be missing, which questions matter and which operational details materially affect performance. They learn how to distinguish a solvable problem from an un-priceable risk.
Those capabilities can travel. Essential, unanchored strip retail can involve similarly granular properties, fragmented ownership and highly local dynamics. Understanding an asset requires close attention to its trade area, tenant quality, consumer demand, leasing risk and competitive supply.
Durable small businesses may present comparable challenges: owner-dependent operations, incomplete systems, uneven reporting and improvement opportunities that emerge only through detailed diligence. The transactions are not identical, but the capabilities required to navigate them can be closely related.
Execution Is The Differentiator
Investors naturally focus on purchase price, cap rates, leverage, rent growth, occupancy and projected returns. Those metrics matter, but they do not necessarily determine who creates the most value after an acquisition. Execution does.
In self-storage, that can mean pricing, digital marketing, customer acquisition, revenue management, technology, labor efficiency and day-to-day management. A facility is not simply a collection of units; it’s an operating business with customers, pricing decisions and processes that can be improved continuously.
The same principle applies elsewhere. A retail property may benefit from better leasing, stronger tenant relationships, tighter expense management or more deliberate capital planning. A small business may benefit from professionalized processes, better reporting, improved customer acquisition or more effective technology.
Value creation does not end at closing. It depends on what happens after ownership changes.
Financial structures can be replicated. An operating culture built through years of detailed execution is much harder to reproduce.
A Repeatable System, Not A Rigid Template
A transferable playbook should not be confused with applying the same strategy everywhere.
Real estate is local. Economic conditions, asset quality, competition, supply, demand drivers and market sentiment can differ materially from one market to another.
A self-storage facility may perform differently depending on supply growth, household density or housing turnover. A retail center may succeed — or struggle — based on trade-area dynamics that do not appear in a broad market report. The value of a repeatable system is not that it assumes every market behaves the same way. It is that core capabilities, such as disciplined underwriting, local-market analysis, sourcing, operational execution and downside protection, can be applied across different environments.
The framework travels. The assumptions do not.
Expansion Without Style Drift
Success in one asset class does not automatically create an advantage in another. Before expanding, investors need to understand what made them successful in the first place.
Was it cheap capital or a favorable market cycle? Or was it a durable capability (sourcing, underwriting, operating, developing or navigating fragmented ownership) that can translate elsewhere? The right question is not whether two asset classes look similar. It is whether the competitive advantages and organizational capabilities required to succeed in them are similar.
Fragmented sectors can become more institutionalized as larger investors seek new places to deploy capital. The opportunity for specialized investors may exist before that transition is complete, particularly where demand is durable, ownership is fragmented and operational improvement remains possible. Self-storage illustrates this dynamic. The sector has become more institutionalized while remaining fragmented enough to reward investors who can source smaller opportunities, work through incomplete information and operate assets intensively.
Self-storage, essential strip retail and durable small businesses are different investments, but each rewards similar capabilities: navigating fragmented ownership, identifying granular opportunities, underwriting imperfect information and improving operations.
The asset class can change. The operating system does not.